Finance
What Is Umbrella Insurance and Do You Need It?
Liability cover that starts where your auto or home limits stop — what triggers a payout, what insurers refuse to pay, and who can skip it.
By Marisol Ferreira · Oct 06, 2026 · 8 min read
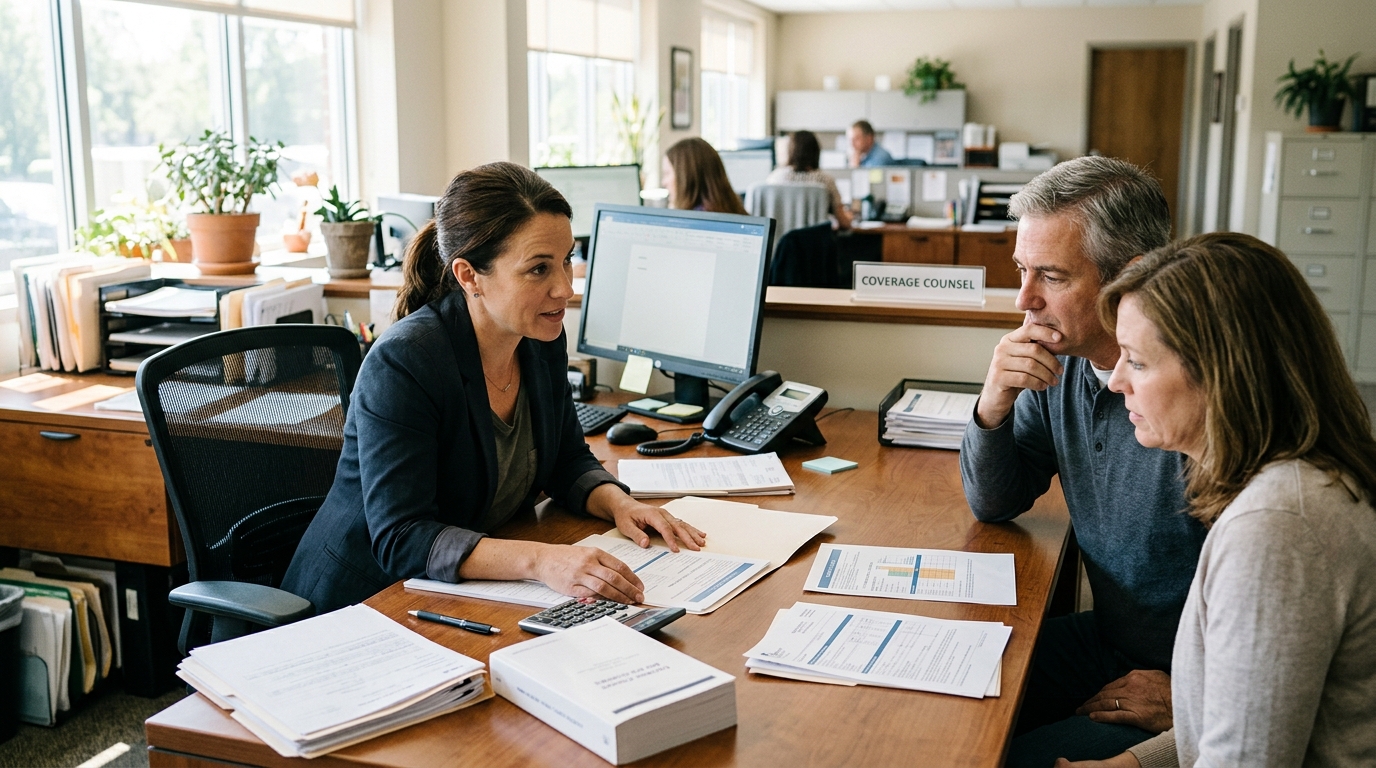
Umbrella insurance is extra liability coverage that pays only after the liability limit on an underlying policy — usually auto, homeowners or renters — has been used up. It does not replace those policies; it extends them, and insurers will not sell it to you unless your underlying limits are already high.
This guide explains the payout trigger, the exclusions written into standard personal umbrella wording, the premium ranges reported by trade bodies and comparison sites, and the household situations where the cost is hard to justify.
What It Actually Covers
Umbrella insurance is liability insurance that provides coverage when a liability claim exceeds the limits of another policy, such as auto or homeowners insurance, and can in some cases act as primary insurance for losses the underlying policies do not cover at all (Wikipedia, undated). The trigger is specific: the underlying liability limit has to be paid out in full first.
Here is how that works in a concrete claim. You rear-end a car on a suburban arterial road, the other driver has a spinal injury, and the settlement plus legal costs come to $500,000. Your auto policy's bodily injury limit is $300,000. The auto insurer pays its $300,000 and stops. Without umbrella coverage, the remaining $200,000 comes out of your own pocket — wages, savings, home equity (NerdWallet, undated). With a $1 million umbrella in force, the umbrella insurer picks up that $200,000 gap, up to its own limit.
The same structure applies to a homeowners liability claim — a guest injured on your property, or a dog bite — where the home policy's personal liability limit is exhausted and the umbrella takes over from there.
Umbrella policies also reach some risks a standard underlying policy often leaves out. Libel and slander are the common examples: if someone sues you over a false written statement (libel) or a false spoken one (slander), an umbrella may pay legal fees and damages, which a typical homeowners policy does not offer (NerdWallet, undated; Insurance Information Institute, undated). When the umbrella is acting as primary cover like this, expect a self-insured retention — a deductible-like amount you pay before the insurer does — stated on your declarations page.
To be sold an umbrella at all, you normally need high underlying limits already in place. Most insurers require at least $250,000 of liability coverage on an auto policy and $300,000 on a homeowners policy before they will issue a $1 million umbrella (Insurance Information Institute, undated). Some set the auto requirement as $250,000/$500,000/$100,000 across all vehicles, plus $300,000 of personal liability on every property you own (CoverageCat, undated). Coverage is then sold in $1 million increments, up to roughly $10 million (The Zebra, undated).
What It Does Not Cover
Standard personal umbrella wording carves out whole categories of claim. These are the ones that show up most often, and the clause that does the work:
- Intentional acts. Damage or injury you caused on purpose, or through a criminal act, is excluded by the intentional-acts clause — typically with a narrow exception for self-defense (Galvez Insurance, undated; CFP Insurance, undated). A bar fight you started is not a covered liability claim.
- Business and commercial liability. Liability arising from business operations is excluded from personal umbrella policies; that exposure needs a separate commercial umbrella policy (Premier Risk, undated; Galvez Insurance, undated). A home-based consultancy sued by a client gets no help from a personal umbrella.
- War. The war exclusion removes liability arising from war, invasion or insurrection (Galvez Insurance, undated).
- Nuclear incidents. Liability connected to a nuclear event is excluded, because that risk sits under a separate federal and pooled-insurance structure (Galvez Insurance, undated).
- Pollution. The pollution exclusion removes liability for the discharge or escape of contaminants — a failing heating-oil tank on a residential property is the classic example (Galvez Insurance, undated).
- Your own injuries and your own property. Umbrella is third-party liability cover. It responds when someone else claims against you; it does not pay to repair your own car or treat your own broken leg.
One more mechanism worth knowing: if you let an underlying policy lapse or drop its liability limit below the minimum the umbrella insurer required, the umbrella typically still only pays above that required limit. The gap created by your reduced underlying cover becomes yours.
What It Costs
Every figure below is an estimate, not a quote. What you actually pay depends on your state, the number of vehicles and licensed drivers in the household, how many properties you own, your claims and driving history, the coverage limit you pick, and the individual carrier's rating.
| Pricing factor | Reported annual premium | Source type |
|---|---|---|
| First $1 million of coverage, typical individual | around $150 to $300 | insurance trade body estimate [a] |
| First $1 million, quoted market range | $150 to $400 | insurance comparison site [b] |
| First $1 million, reported average | $383 | carrier risk-services report cited by a comparison site [c] |
| First $1 million, bundled with home and auto at one insurer | $131, as reported by a single policyholder | individual policyholder account [d] |
| Each extra $1 million tier, up to about $10 million | roughly $50 to $75 per tier | insurance comparison site [e] |
Footnotes:
- [a] Insurance Information Institute (III) estimate, undated, cited by Hippo Insurance Services.
- [b] CoverageCat, undated.
- [c] ACE Private Risk Services report, undated, cited by Insurify.
- [d] Ramsey Solutions, undated — one policyholder's reported bundled price, not a market average.
- [e] The Zebra, undated.
Two things the headline price hides. First, the step up to the required underlying limits — $250,000 auto and $300,000 home liability (Insurance Information Institute, undated) — may raise your existing premiums before the umbrella premium is even added. Compare the total of all three policies, not the umbrella line alone. Second, the per-million cost falls sharply after the first tier: at roughly $50 to $75 for each additional million (The Zebra, undated), going from $1 million to $3 million usually costs less than the first million did.
Is It Worth Adding
Worth the premium: the household with a named lifestyle risk. You have an in-ground pool and host summer parties, you rent out a second property, you keep a dog, or you have a teenage driver on the policy — the Insurance Information Institute (undated) names all four as reasons to consider an umbrella. These are the situations where a single claim realistically runs past a $300,000 home liability limit or a $300,000 auto bodily injury limit. A pool-party head injury or a teen driver's multi-car crash is exactly the $500,000-total, $200,000-gap arithmetic described earlier (NerdWallet, undated).
Worth the premium: the household with attachable assets above its underlying limits. If you have $400,000 of home equity plus a $250,000 taxable brokerage account, a judgment that exceeds your $300,000 auto limit reaches those assets. Paying somewhere in the region of $150 to $400 a year for $1 million of coverage (CoverageCat, undated) is cheap relative to a $200,000 personal exposure.
Not worth it: the renter with little to attach and modest income. If you rent, do not own a car, have about $5,000 in savings and no dependents, a $300,000 renters liability limit already exceeds what a claimant could collect from you. The umbrella premium buys protection against a dollar exposure you do not currently have.
Not worth it: the person whose main risk is their business. If your real exposure is a client suing your single-member LLC, a personal umbrella does nothing — business-operations liability is excluded and requires a separate commercial umbrella (Premier Risk, undated). Buying the personal policy here leaves the actual gap open. Price the commercial cover instead.
If you are between these profiles, the useful test is arithmetic, not instinct: add up what a claimant could realistically take from you — home equity, non-retirement savings, future wages subject to garnishment in your state — and compare it with your current auto and home liability limits. Garnishment and homestead-exemption rules differ by state, so the attachable figure is not the same everywhere.
Frequently asked questions
Do I have to buy my home and auto insurance from the same company to get an umbrella?
Not always, but most insurers require specific underlying limits before issuing one — commonly $250,000 of auto liability and $300,000 of homeowners liability (Insurance Information Institute, undated). Some will only write the umbrella if they also hold those underlying policies. Bundling can lower the price: one policyholder reported $131 a year bundled (Ramsey Solutions, undated).
How much umbrella coverage should I buy?
Coverage is sold in $1 million increments up to roughly $10 million, with each tier after the first adding about $50 to $75 a year (The Zebra, undated). A common starting point is matching your attachable assets — home equity plus non-retirement savings — above your existing auto and home liability limits.
Does umbrella insurance cover my own medical bills after a crash?
No. Umbrella is third-party liability cover — it pays when someone else claims against you and your underlying limit is exhausted. Your own injuries fall to health insurance, medical payments or personal injury protection on the auto policy. Your own vehicle damage falls to collision coverage.
Will it pay if someone sues me over something I posted online?
Possibly. Umbrella policies may pay legal fees and damages for libel (a false written statement) or slander (a false spoken one) — coverage a typical homeowners policy does not include (NerdWallet, undated). The intentional-acts exclusion still applies, and an umbrella acting as primary cover usually carries a self-insured retention.
Does a personal umbrella cover my side business?
No. Liability arising from business or commercial operations is excluded from personal umbrella policies and needs a separate commercial umbrella (Premier Risk, undated). That applies to a rental operated as a business, freelance work and delivery driving. Renting out a property is still cited as a reason to review your limits (Insurance Information Institute, undated).
Sources
- Insurance Information Institute (III) — Should I purchase an umbrella liability policy?
- Hippo Insurance Services — Umbrella Insurance Uncovered: [Asset Protection 101]
Written by
Marisol Ferreira
Marisol untangles the daily noise of equities and bonds to find what actually moves portfolios. She writes with a skepticism toward consensus calls and a fondness for footnotes. Her beat is where macro theory meets messy reality.