Finance
What to Do If Your Debit Card Is Declined but You Have Money
A balance on screen is not the same as money you can spend today — holds, pre-authorizations and posting times all sit between the two.
By Renata Ibarra · Oct 06, 2026 · 8 min read
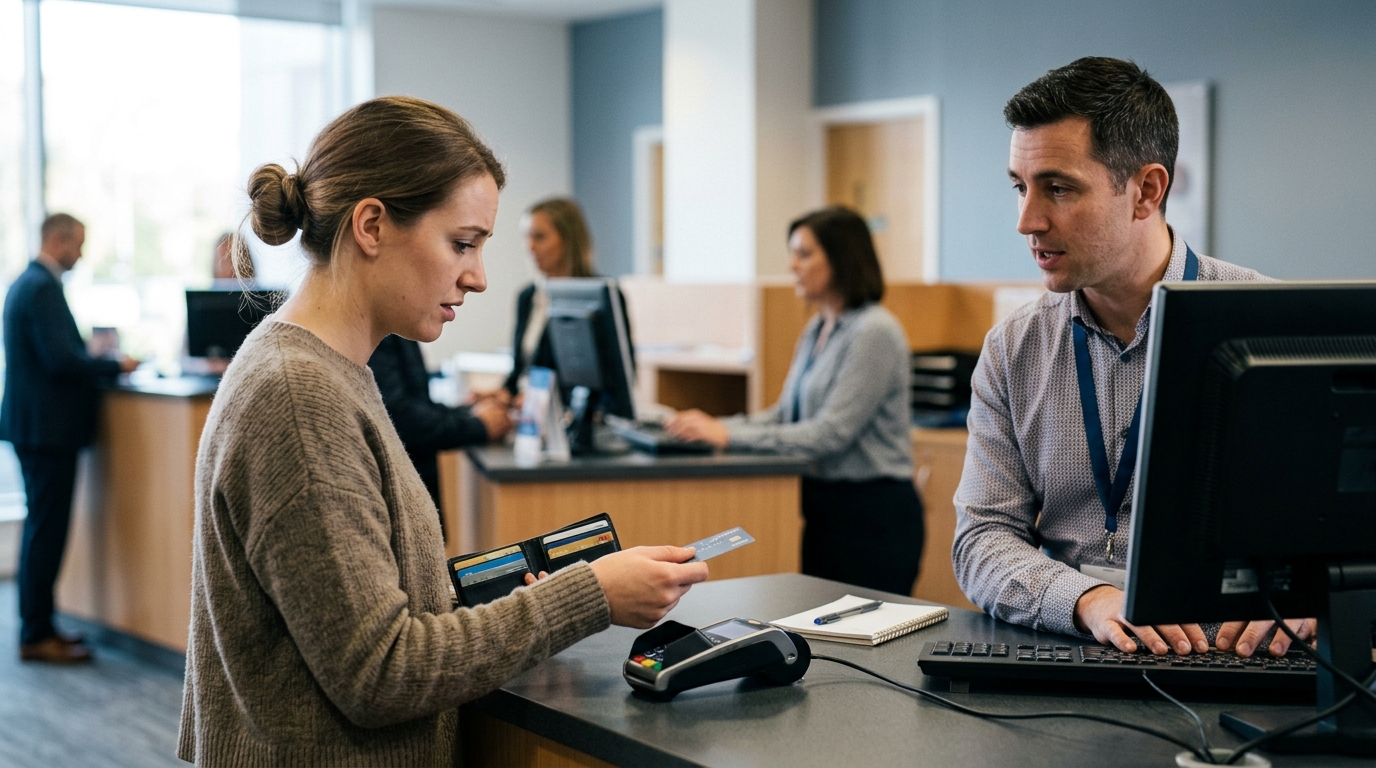
A debit card declines when the money is not available, not when it is not there. The gap usually comes from a deposit hold, a merchant pre-authorization that has not released, or a transfer that has not finished posting — and each one has a schedule you can ask about by name.
This guide explains the common mechanics, the order to work through them, and the paperwork to have in hand before you call.
Why This Happens
Your debit card draws on your checking account's available balance. Several things can shrink that number while the ledger balance still looks healthy.
A Regulation CC hold on a deposit. Under Regulation CC, up to a set dollar amount of a day's check deposits must be available by the start of business on the next business day, with the rest released later (National Credit Union Administration (NCUA), undated). Credit unions must generally make check-deposit funds available no later than the second business day after the day of deposit (National Credit Union Administration (NCUA), undated). Deposit cash or a check at an ATM your institution does not own and the money need not be available until the fifth business day after the deposit day (National Credit Union Administration (NCUA), undated). These are business days, not calendar days — a Friday deposit over a holiday weekend stretches further than it looks.
A new-account exception. Regulation CC lets an institution place a longer hold on check deposits into an account open fewer than 30 calendar days (Abrigo, undated). The next-business-day minimum and the thresholds used for new-account, large-deposit and repeatedly-overdrawn exception holds both increased effective July 1, 2025 (BHC Community Credit Union (BHCCU), 2025-07), so the number in an older account disclosure may be out of date. Ask for the current figure.
A merchant pre-authorization that has not released. Visa's rules give card-present retail and gas-station merchants a window to capture an authorization, a longer window for card-not-present orders such as online or phone purchases, and a longer window still for hotels, car rentals and cruise lines (LegalClarity, undated). Until the merchant captures or the authorization expires, that amount is subtracted from what you can spend. Visa and Mastercard allow gas stations a pre-authorization hold up to a cap that was raised from $125 in April 2022 to reflect higher fuel prices (LegalClarity, 2022-04) — a $20 fill-up can tie up far more than $20 for a day or two.
ACH timing. Direct deposits and transfers in from another institution travel as ACH entries and post in batches on business days. A transfer initiated Friday evening can show as "pending" all weekend and not be spendable until the next business day.
Limits and blocks. Many checking accounts carry a daily debit-card purchase limit and a separate daily ATM withdrawal limit, and fraud monitoring can block a card after an out-of-pattern transaction. Also check which account the card is tied to: a debit card is issued against checking, and an overdraft-protection sweep from savings may not fire if the linked savings balance is short.
How to Fix It
- Open your app or online banking and compare the available balance with the current (ledger) balance. If they differ, the difference is a hold or a pending authorization, and the fix is time, not a phone call.
- Call the number on the back of the card and ask for the card services or debit card department. Say: "My card declined at [merchant] on [date] for $[amount]. Was it declined by you or by the merchant, and was there a fraud block, a daily purchase limit, or an insufficient available balance?" Ask them to list every hold and its release date.
- If a deposit is being held, ask the deposit operations or branch staff for the hold reason and the release date in business days. Useful wording: "Which Regulation CC exception are you using — new account, large deposit, or repeatedly overdrawn — and what date will the full amount be available?"
- If the hold belongs to a merchant, call the merchant, not the bank. Ask the merchant to void or release the unused portion of the pre-authorization and to give you the authorization code and the date it was placed.
- If a charge on the account is wrong or unauthorized, give notice of error in writing as well as by phone. Under Regulation E the institution must determine whether an error occurred within a set number of business days of your notice; if it cannot finish in 10 business days it may take longer only if it provisionally credits your account within 10 business days of receiving the notice (America's Credit Unions, undated). It must tell you the amount and date of that credit, and report the investigation results, within set numbers of business days (CrossCheck Compliance LLC, undated). Ask for both deadlines in writing.
- If the answer does not come, escalate. Submit a complaint to the Consumer Financial Protection Bureau, which generally requires the company to respond within a set number of calendar days, with a final response due later if the first is not final (Consumer Financial Protection Bureau (CFPB), undated). For an FDIC-supervised bank, you can also submit a complaint or inquiry online through the FDIC Information and Support Center or by mail to the Consumer Response Unit (Federal Deposit Insurance Corporation (FDIC), undated). For a federally insured credit union, the NCUA handles consumer complaints.
Before You Call or Visit
Tick each line as have it or don't have it. Missing items are the usual reason a call ends with "we'll have to look into it."
| Item | Have it or don't |
|---|---|
| Checking account number and routing number | Needed before anyone discusses holds |
| The exact date and time of the decline | Business day matters for Regulation CC and Regulation E counts |
| The merchant name as it appears on the statement | Pre-authorizations often post under a different trading name |
| The dollar amount attempted, and the amount showing as pending | The gap is usually the pre-authorization |
| Screenshot of available balance vs. current balance | Timestamped evidence of the gap |
| Deposit receipt, with deposit date and whether it was an owned or non-owned ATM | Drives the second- vs. fifth-business-day schedule |
| The account opening date | Under 30 calendar days triggers the new-account exception |
| Your account disclosure showing daily debit-card purchase and ATM limits | So you can tell a limit from a block |
| Any prior correspondence, with dates and reference numbers | Starts the escalation clock where you left it |
| A written notice of error, if a charge is disputed | Phone notice alone can leave the Regulation E timeline arguable |
Frequently asked questions
An unauthorized debit emptied my balance and caused the decline. How fast must my institution act?
Regulation E requires the institution to determine whether an error occurred within a set number of business days of your notice. If it cannot finish within 10 business days, it may take longer only if it provisionally credits your account within 10 business days of receiving the notice (America's Credit Unions, undated). It may withhold a portion of that credit while investigating a transfer it reasonably believes was unauthorized (America's Credit Unions, undated). It must tell you the amount and date of the credit, and report results after completing the investigation, within set numbers of business days (CrossCheck Compliance LLC, undated). The 10-business-day clock can be extended if the transfer was to or from an account within 30 days of its first deposit (CrossCheck Compliance LLC, undated).
My card was lost or stolen. How much can I be charged?
Regulation E caps a debit cardholder's liability for fraudulent charges at a set amount if you report the lost or stolen card within two business days of discovering it (Consumer Action, undated). Report after the unauthorized use but within 60 days and your liability can be higher (Consumer Action, undated). Those are the two dates that matter — report the same day you notice, and get the report reference number in writing. Ask your institution for the current dollar caps, which are set in Regulation E itself.
Does Regulation E cover a check I deposited or a check someone cashed against me?
No. Regulation E error rights cover electronic fund transfers from a consumer checking or savings account — debit card purchases, ATM withdrawals and ACH debits. Paper check problems run through different rules: availability of deposited checks is Regulation CC (second business day for credit union check deposits, fifth business day for deposits at a non-owned ATM; National Credit Union Administration (NCUA), undated), and a forged or altered check is a claim under your deposit agreement and state law. Do not file one as the other, or the deadlines will not apply.
Who do I complain to if the bank will not release a deposit hold?
Submit a complaint to the CFPB, which generally requires the company to respond within a set number of calendar days, with a final response due later if the first response is not final (Consumer Financial Protection Bureau (CFPB), undated). For an FDIC-supervised bank you can file online through the FDIC Information and Support Center or by mail to the Consumer Response Unit (Federal Deposit Insurance Corporation (FDIC), undated); for a federally insured credit union, file with the NCUA. Include the deposit date, amount and the exception the institution named.
Sources
- National Credit Union Administration (NCUA) — Expedited Funds Availability Act (Regulation CC)
- Abrigo — Reg CC new account hold: Funds availability & fraud risks
Written by
Renata Ibarra
Renata shapes the publication's voice and keeps its coverage honest when markets get loud. She edits with a focus on precision, especially around risk and uncertainty. She also writes occasional essays on how financial language shapes financial behavior.