Finance
How to Switch From a Big Bank to a Credit Union Without Losing a Payment
Direct deposit, autopay and card-on-file charges each move on their own clock, and the order you move them is what decides whether anything bounces in week one.
By Priya Chandrasekaran · Oct 06, 2026 · 8 min read
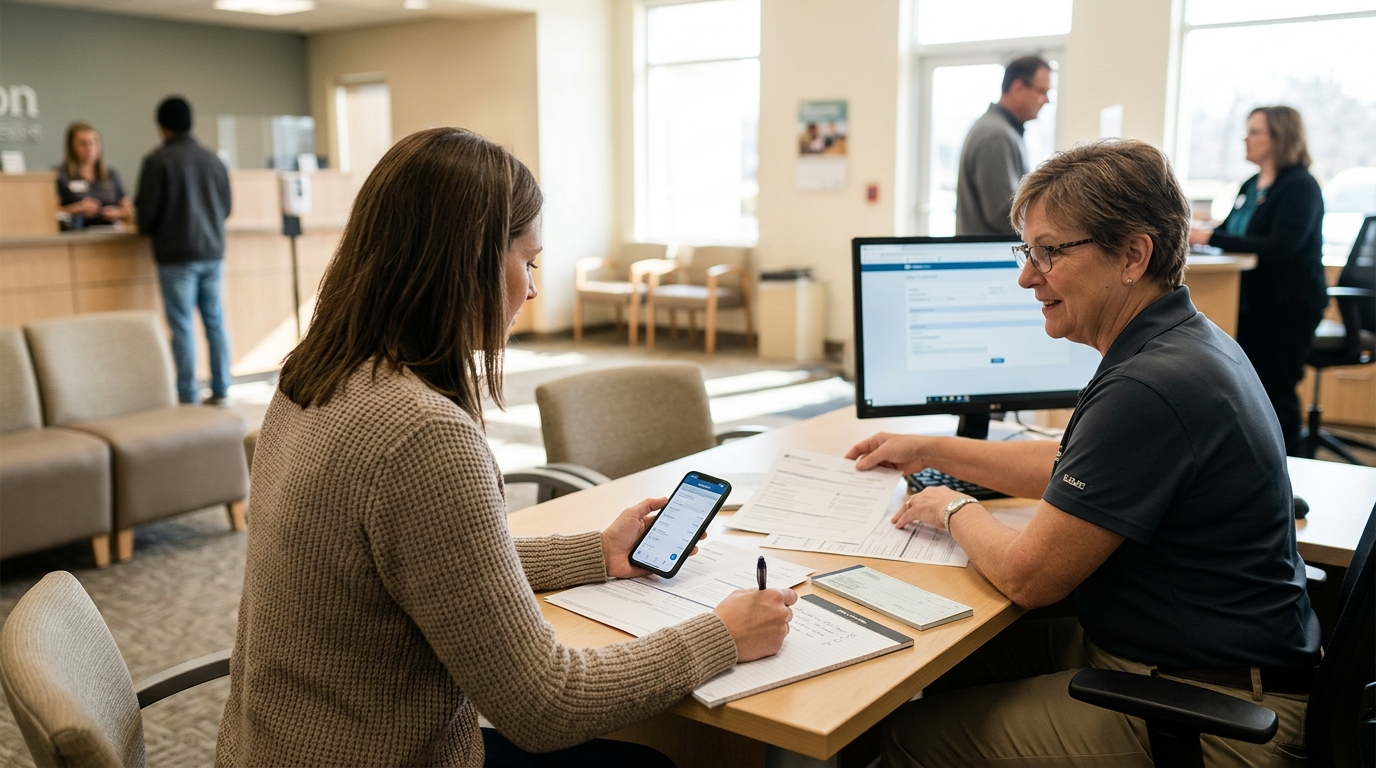
Moving your everyday money to a credit union is mostly a sequencing problem. The new share draft (checking) account can be open in a single visit, but the direct deposit, the autopays and the subscriptions billed to your debit card each take their own number of days to redirect — so the old account has to stay open and funded while they catch up.
Plan on about 30 calendar days from opening the new account to closing the old one. Below is the order that keeps payments landing where they should.
Step-by-Step
- Confirm you are eligible to join (same day, about 15 minutes). A federal credit union's field of membership — the people, employers, organisations and areas it may serve — is set in its charter under the NCUA's chartering process, so eligibility depends on meeting that specific credit union's defined field of membership (National Credit Union Administration, undated). Check this before you gather anything else.
- Compare accounts before you open one (1–2 business days). The Consumer Financial Protection Bureau's checklist for moving a checking account advises shopping around and comparing account services, online or in person, to help avoid accidental bounced payments and other disruptions (Consumer Financial Protection Bureau, undated). Ask for the fee schedule in writing and get the exact numbers: the monthly fee on the share draft account and the balance or direct-deposit amount that waives it, the overdraft and non-sufficient-funds fee per item, and the out-of-network ATM fee.
- Open the share savings and share draft accounts and fund them (Day 0, about 45 minutes). Credit union membership usually starts with a share savings account holding a minimum par value deposit — ask what that amount is, since each credit union sets it. The share draft account is the checking account. Fund it with cash or a transfer, not a large check, because of the new-account hold rules below.
- List every recurring credit and debit from two months of old statements (1 business day). Separate them into three buckets: direct deposits in, ACH autopays pulled out, and card-on-file charges billed to your old debit card. The third bucket is the one people forget.
- Redirect direct deposit (1–2 pay cycles). Give payroll the new routing number and share draft account number, then ask which specific pay date the change takes effect. Until you have confirmation of that date, treat the old account as still live.
- Move ACH autopays one at a time, then card-on-file charges (2–5 business days each). Change each biller at its own website, and leave enough in the old checking account to cover one more cycle of each in case the change misses the cut-off.
- Run both accounts in parallel for about 30 calendar days (two statement cycles). Watch the old statement for anything you missed — annual renewals and quarterly bills are the usual stragglers.
- Close the old checking account in writing and get a zero-balance confirmation (1–2 business days). Ask for written confirmation that the balance is zero, the account is closed, and no monthly fee will post after closure. Keep the final statement.
What to Have Ready
The Consumer Financial Protection Bureau's checklist for moving a checking account tells you to ask the new institution what identification it requires before opening (Consumer Financial Protection Bureau, undated). Call and ask that exact question, then gather:
- An unexpired government photo ID — driver's licence, state ID, passport or permanent resident card. Some credit unions ask for a second form of ID.
- Your Social Security number or ITIN, as it appears on your card or tax return.
- Proof of your current address if your ID is out of date — a utility bill or lease dated within the last 60 days is the usual request.
- Proof you meet the field of membership — an employer badge, pay stub, union card, school ID, or proof of address in the service area, depending on the charter (National Credit Union Administration, undated).
- The opening share deposit, in cash or by transfer. Ask the exact dollar amount of the par value share when you call about ID.
- Your old account and routing numbers, taken from a statement or a voided check — not from memory.
- Two months of old checking statements, for building the recurring-payment list.
- Login details for every biller and subscription that has your old debit card number on file.
- Beneficiary names, dates of birth and Social Security numbers, if you want payable-on-death designations, which also affect how the $250,000 insurance limit applies across ownership categories.
What Happens and When
| Day | What happens |
|---|---|
| Day 0 | You open the share savings and share draft accounts and make the opening deposit. Cash handed to an employee in person must be available no later than the first business day after deposit; if not made in person, no later than the second business day (National Credit Union Administration, December 2025). |
| Day 1–2 | Debit card and PIN are ordered; online banking is set up. New-account hold rules apply: the first $225 of daily check deposits is available the next business day, and amounts over $5,525 can be held until the ninth business day. Regulation CC sets no time limit at all on local check deposits into new accounts (National Credit Union Administration, December 2025). |
| Day 3–5 | Debit card typically arrives; activate it and update card-on-file subscriptions. A check or cash put into a nonproprietary ATM must be available no later than the fifth business day after deposit (National Credit Union Administration, December 2025) — so avoid ATM deposits this week. |
| Day 6–10 | Direct deposit paperwork reaches payroll. Move ACH autopays over, leaving one cycle's worth of funds in the old checking account. |
| Day 11–30 | First direct deposit lands in the new share draft account. Confirm the amount matches, then stop funding the old account beyond its remaining autopays. |
| Day 30–45 | First full statement from the credit union. Reconcile it against your recurring-payment list, then close the old checking account in writing. |
| Day 60 | The outer edge of your Regulation E statement window: report any unauthorised electronic transfer within 60 days of the institution sending that statement to avoid liability for later unauthorised transfers (Consumer Financial Protection Bureau, undated). |
Frequently asked questions
Is my money as protected at a credit union as at a big bank?
The NCUA's National Credit Union Share Insurance Fund protects accounts at federally insured credit unions up to $250,000 per share owner, per insured credit union, for each account ownership category (Apple Federal Credit Union restating NCUA share insurance rules, undated). That is the same standard limit that applies at FDIC-insured banks. Share savings and share draft balances you hold in the same ownership category are added together toward the single $250,000 figure, so splitting between checking and savings at one credit union does not double the coverage.
Why is my first big check deposit held longer than it was at my old bank?
Because the account is new. Under Regulation CC, the first $225 of your daily aggregate check deposits must be available the next business day, but the portion of a specified check deposit above $5,525 can be held until the ninth business day, and there is no regulatory time limit at all on local check deposits into new accounts (National Credit Union Administration, December 2025). Fund the switch with cash or an electronic transfer for the first 30 days.
A charge on my new debit card is wrong. What are my rights?
Regulation E covers electronic transfers — debit card, ATM and ACH. If you report a lost or stolen card within two business days of learning of the loss, your liability is capped at the lesser of $50 or the amount of the unauthorised transfers (Consumer Financial Protection Bureau, undated). Wait longer than two business days and the second tier allows liability up to $500 for transfers in that gap (Consumer Financial Protection Bureau, undated). Paper check disputes are not Regulation E claims and follow different rules, so say explicitly whether you are disputing a card transaction or a check.
How long should I really leave the old checking account open?
About 30 calendar days, covering two statement cycles, and longer if you have quarterly or annual bills on autopay. Closing on day 5 is the most common cause of a bounced payment, and a single non-sufficient-funds fee at the old bank usually costs more than a month of keeping the account at a zero-fee balance.
Will my share savings account have transfer limits?
Ask the credit union two things: whether it still applies a monthly limit on withdrawals and transfers from share savings — a Regulation D-era practice many institutions kept — and the exact per-item fee for each transfer above that limit. Share draft (checking) accounts are not subject to that limit, which is why recurring autopays belong there rather than in savings.
Sources
- Consumer Financial Protection Bureau — § 1005.6 Liability of consumer for unauthorized transfers (Regulation E)
- National Credit Union Administration — Expedited Funds Availability Act (Regulation CC) — Federal Consumer Financial Protection Guide (2025-12)
Written by
Priya Chandrasekaran
Priya breaks down earnings calls, mergers, and balance sheets for readers who don't speak spreadsheet. She's most interested in how companies justify the numbers they report. Her columns favor clarity over jargon.