Finance
Should You Choose a Credit Union or a Traditional Bank Account?
Member-owned cooperatives and for-profit banks price fees, overdrafts and ATM access differently — here is where the gap shows up on your statement.
By Desmond Okafor · Oct 06, 2026 · 10 min read
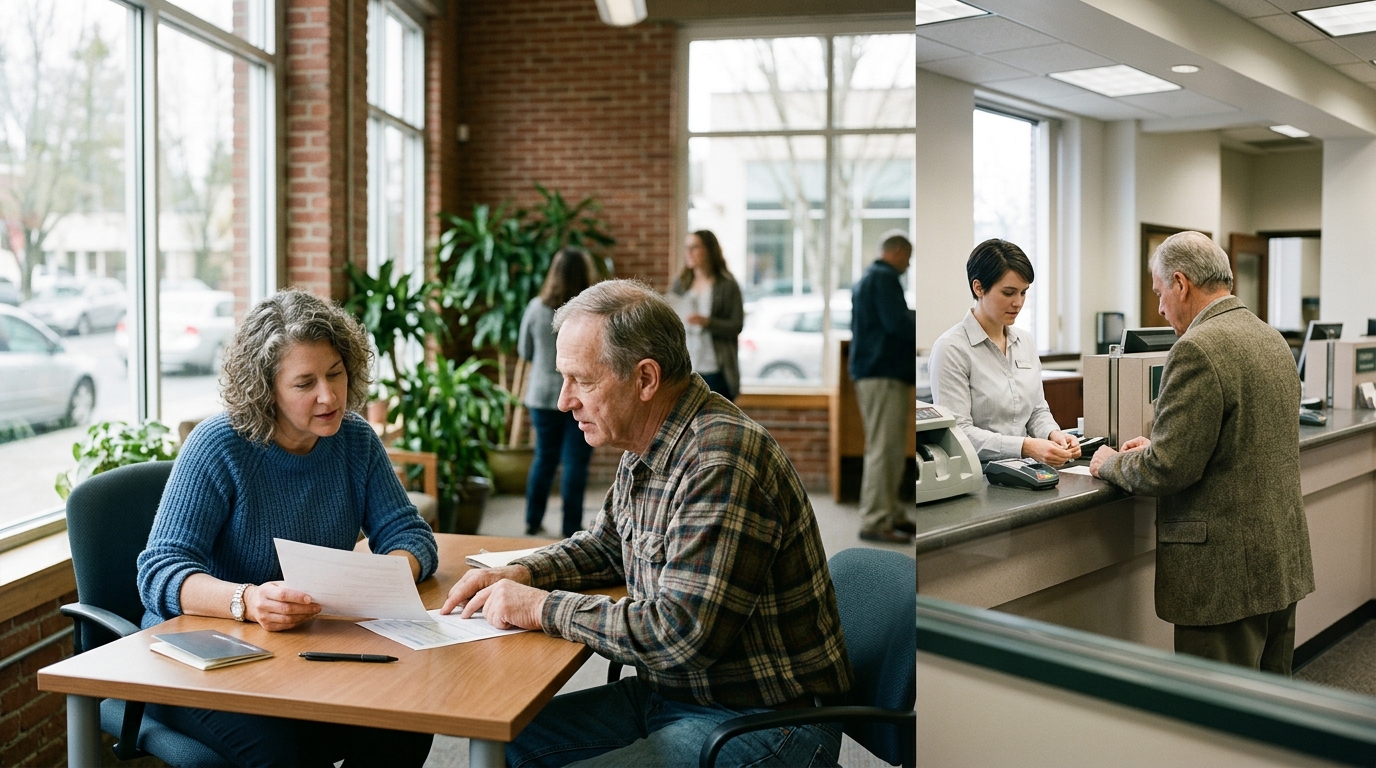
The choice between a credit union and a traditional bank is not a safety question — federally insured deposits are protected to the same $250,000 standard limit on both sides. It is a question of what you pay each month, what happens when you overdraw, how far your ATM access reaches, and whether you can even join.
This guide lines up the two against the same criteria, names the regulations behind your holds and dispute rights, and points to the three or four numbers on a fee schedule that decide the answer for you.
How These Accounts Actually Differ
The structural difference is ownership. A credit union is a not-for-profit cooperative owned by its members, so earnings come back as rates and fee schedules; a bank is a for-profit company that answers to shareholders. Everything below is downstream of that — but the size of the gap is set by each individual institution, not by the charter type, so you compare the two documents in front of you.
Monthly maintenance fee (checking). The average monthly maintenance fee on non-interest checking is $5.47, and nearly half — 47% — of those accounts charge nothing at all (Bankrate, 2024 Checking and ATM fee study). Interest-bearing checking is a different product: it averages $15.65 a month, with an average minimum balance of $10,705 required to waive it (Bankrate). A separate survey put the average monthly checking maintenance fee at $13.95, or $167.40 a year (MoneyRates.com, undated). Find the waiver trigger before you sign and check it is one you hit every single month — a direct deposit amount, a balance floor, or a card-transaction count.
Minimum opening deposit. At a credit union you buy a membership share to join, and that share deposit usually has to stay on the books for as long as you are a member; the dollar amount sits in the membership agreement. A bank has no share purchase, only whatever opening deposit its account disclosure states. Ask both: what is the minimum opening deposit, and does any part of it have to stay in the account?
Overdraft handling (checking only). The average overdraft fee is $27.08 and the average nonsufficient funds fee is $17.72 (Bankrate, 2024 study). Those are two different events: one pays the item and charges you, the other returns it. Under Regulation E you must opt in before an institution can charge overdraft fees on one-time debit card and ATM transactions — if you never opt in, those transactions are declined instead.
Interest rate (savings). Neither charter guarantees a better APY. Both must disclose the APY, the balance tiers it applies to, and any compounding method in writing under the Truth in Savings rules before you open. Compare today's posted APY on each institution's rate sheet, not last year's.
ATM and branch network. A large bank gives you its own branded ATMs and branches. A credit union typically buys reach through shared networks instead: participating members get nearly 30,000 surcharge-free ATMs and more than 5,900 shared branch and self-service locations covering all 50 states through CO-OP shared branching (Clackamas Community Federal Credit Union, undated). Going outside whatever network you have costs an average of $4.77 per withdrawal (Bankrate, 2024 study).
Side-by-Side Comparison
| Criterion | Credit union | Traditional bank |
|---|---|---|
| Who the earnings go to | Members, as rates and fees | Shareholders |
| Eligibility | Yes — you must meet a field of membership (employer, geography, family or association) | No membership test; open to any applicant who clears ID checks |
| Monthly fee, non-interest checking | Set in the published fee schedule; sector average $5.47, with 47% of such accounts at $0 (Bankrate, 2024) | Set in the published fee schedule; same sector averages apply (Bankrate, 2024) |
| Monthly fee, interest checking | Average $15.65, waived at an average $10,705 balance (Bankrate) | Average $15.65, waived at an average $10,705 balance (Bankrate) |
| Minimum opening deposit | Membership share purchase required; dollar amount stated in the membership agreement | No share purchase; amount stated in the account disclosure |
| Savings APY | Disclosed in writing under Truth in Savings before you open | Disclosed in writing under Truth in Savings before you open |
| Overdraft / NSF fee, checking | Averages $27.08 overdraft and $17.72 NSF (Bankrate, 2024); Reg E opt-in required for one-time debit and ATM overdrafts | Averages $27.08 overdraft and $17.72 NSF (Bankrate, 2024); Reg E opt-in required for one-time debit and ATM overdrafts |
| ATM access | CO-OP shared branching: nearly 30,000 surcharge-free ATMs, 5,900+ shared branches, all 50 states (Clackamas Community FCU, undated) | Proprietary ATM and branch network; out-of-network withdrawals average $4.77 (Bankrate, 2024) |
| Deposit insurance | NCUA share insurance, $250,000 per member per ownership category (NCUA, undated) | FDIC insurance, $250,000 per depositor, per insured bank, per ownership category (FDIC, undated) |
| Savings withdrawal cap | Six-per-month limit removed from the Reg D savings-deposit definition effective 24 April 2020; excess-transaction fees are still allowed by policy | Same Reg D change, effective 24 April 2020; excess-transaction fees still allowed by policy |
| Check hold rules | Regulation CC: first $275 next business day; new-account exception threshold $6,725, both effective 1 July 2025 | Regulation CC: identical $275 and $6,725 figures, effective 1 July 2025 |
| Debit card error rights | Regulation E error-resolution process | Regulation E error-resolution process |
Where the two columns read the same, the regulation is federal and the charter does not change it. The rows that differ — eligibility, ATM reach, and who the profit belongs to — are the ones worth deciding on.
Who Each Option Fits Best
- You overdraw more than once a month. Trigger: two overdrafts in a typical month costs roughly $54 at the $27.08 average (Bankrate, 2024). Whichever institution you pick, ask for the per-day cap, the grace amount, and whether a linked-savings transfer is free — and decide deliberately whether to opt in under Reg E for one-time debit and ATM overdrafts, or leave those transactions to decline.
- Your paycheck or balance sits below the waiver line. Trigger: you cannot reliably hold $10,705, the average balance needed to waive the $15.65 monthly fee on interest-bearing checking (Bankrate). Then a no-fee non-interest checking account is the better structure — 47% of those charge $0 a month (Bankrate, 2024) — and that is available at both credit unions and banks, so compare the two fee schedules directly.
- You travel, move between states, or work away from home. Trigger: more than three or four out-of-network ATM withdrawals a month at an average $4.77 each (Bankrate, 2024). A credit union in the CO-OP shared branching network gives nearly 30,000 surcharge-free ATMs and 5,900+ shared branches across all 50 states (Clackamas Community FCU, undated). Note that CO-OP ATM deposits are typically available within two business days (Signature Federal Credit Union, undated) — slower than cash handed over a counter.
- You deposit cash daily or need same-week access to large checks. Trigger: you regularly deposit more than $275, the Reg CC next-business-day minimum as of 1 July 2025. Cash deposited in person and electronic payments such as ACH credits and wire transfers must generally be available by the next business day after the banking day of deposit (Webster First Federal Credit Union, undated) — so counter and branch density matters more than app features here.
- You hold more than $250,000 in deposits. Trigger: your combined balances exceed the standard limit at one institution. Both FDIC and NCUA coverage is per depositor or member, per institution, per ownership category (FDIC, undated; NCUA, undated), so splitting across a bank and a credit union insures both sides in full. Note that the NCUA does not insure stocks, bonds, mutual funds, life insurance, annuities or municipal securities, even when sold at a federally insured credit union (NCUA, undated).
Frequently asked questions
Is money at a credit union as safe as money at a bank?
At a federally insured credit union, NCUA share insurance covers up to $250,000 in each member's account, based on ownership category (National Credit Union Administration, undated). FDIC insurance covers up to $250,000 per depositor, per insured bank, for each ownership category (Federal Deposit Insurance Corporation, undated). The limit is the same; the insurer is different. Neither covers investments — the NCUA does not insure stocks, bonds, mutual funds, life insurance policies, annuities or municipal securities even if they are sold at a federally insured credit union (NCUA, undated). One rule to diary: under an NCUA trust-account amendment effective 1 December 2026, each owner's trust shares will be insured up to $250,000 multiplied by the number of trust beneficiaries, to a maximum of $1,250,000 per credit union.
Am I still limited to six withdrawals a month from savings?
Not as a federal matter. Effective 24 April 2020, the Federal Reserve amended Regulation D to remove the six-per-month limit on transfers and withdrawals from the definition of a savings deposit (Consumer Finance Monitor, 2020). That change applied to savings and money market accounts, never to checking. Individual banks and credit unions may still keep their own excess-transaction limits and fees in the account agreement, so check the current savings disclosure for the words 'excess transaction' before you assume unlimited transfers.
How long can a deposit be held before I can spend it?
Regulation CC sets the floor. Effective 1 July 2025, the minimum that must be made available by the next business day from most check deposits rose from $225 to $275 (CliftonLarsonAllen, 2025). For accounts open a short time, the new-account exception threshold rose from $5,525 to $6,725 on the same date. Cash deposited in person, ACH credits and wire transfers must generally be available by the next business day after the banking day of deposit (Webster First Federal Credit Union, undated). Note 'business days' excludes weekends and federal holidays. Deposits made at a CO-OP network ATM are typically available within two business days (Signature Federal Credit Union, undated).
Are my dispute rights different for a debit card charge and a bounced check?
Yes, and the distinction matters. Unauthorised or erroneous electronic fund transfers — debit card purchases, ATM withdrawals, and preauthorised electronic debits — run through the Regulation E error-resolution process, which sets a notice deadline measured from when your statement was sent and requires the institution to investigate and report back. Paper check disputes are not Reg E matters; they fall under your state's UCC rules and your deposit agreement. Consumer ACH debits have their own return window under the network's operating rules. Ask your institution which process it is applying and what the notice deadline is in days for your specific transaction type.
Should I keep accounts at both?
It is allowed, and insurance is counted per institution — $250,000 per depositor per FDIC bank (FDIC, undated) and $250,000 per member at a federally insured credit union (NCUA, undated) — so two institutions double your insured ceiling for the same ownership category. The cost of splitting is duplicate monthly fees unless both accounts meet their waiver triggers, which average $10,705 in balance on interest-bearing checking (Bankrate). Bear in mind that the average brick-and-mortar checking customer has kept the same account for 19 years (Bankrate), so inertia is the real risk: set a calendar reminder to re-read the fee schedule each year.
Sources
- Federal Deposit Insurance Corporation — Understanding Deposit Insurance
- National Credit Union Administration — Share Insurance Coverage
Written by
Desmond Okafor
Desmond covers personal finance with an eye for the small decisions that compound into big outcomes. He's drawn to budgeting tools, debt payoff strategies, and the psychology behind spending. He writes for readers who feel behind and want a clear next step.