Finance
Checking vs. Savings: Which Account Fits Your Spending Habits
One account is built for money moving out every week, the other for money sitting still — and the fee schedule is where that split shows up.
By Marisol Ferreira · Oct 06, 2026 · 9 min read
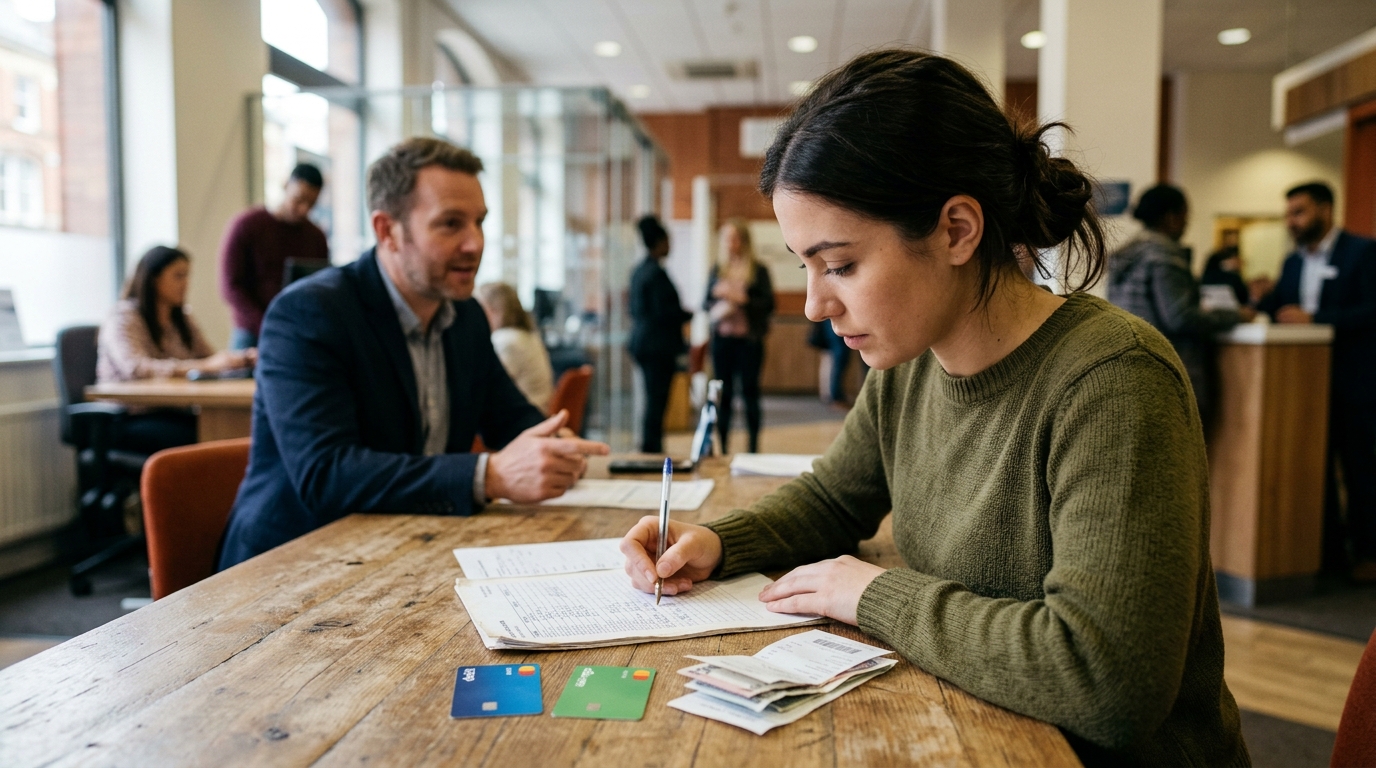
Checking and savings are both deposit accounts with the same federal insurance behind them, but they are priced and restricted for opposite jobs. Checking is built for payments going out: a debit card, bill pay, ATM withdrawals, usually little or no interest. Savings is built for a balance that stays put: an interest rate, fewer ways to spend from it, and sometimes a bank-imposed cap on transfers out.
Before you sign, the three documents that answer almost every question are the fee schedule, the Truth in Savings (Regulation DD) disclosure with the APY on it, and the funds availability policy disclosure required by Regulation CC. Everything below tells you what to look for in them.
How These Accounts Actually Differ
Monthly fee and the waiver trigger. Checking accounts commonly carry a maintenance fee somewhere in the $0 to $15 per month range; basic savings accounts commonly sit in the $0 to $10 range. The fee itself matters less than the waiver condition, and that condition is always a number: a minimum daily balance, a minimum average monthly balance, a direct deposit of at least a stated dollar amount per statement cycle, or a set count of debit card purchases. Find the exact figure on the fee schedule before you open, because a checking waiver that requires a $1,500 daily balance is a different product from one that requires a single direct deposit of any size.
Minimum opening deposit. Both types commonly open with $0 to $100. A low opening deposit is not the same as a low ongoing balance requirement — plenty of accounts open at $25 and then charge monthly unless you hold several hundred or several thousand dollars.
Interest. Standard checking frequently pays 0.00% APY. Rewards or high-yield checking pays interest only if you complete a stated number of debit transactions and receive a direct deposit each cycle, and it usually caps the high rate at a balance ceiling. Savings pays a variable APY that the bank can change at any time; the current number is on the Truth in Savings (Regulation DD) disclosure, not in the advertising.
Overdraft handling. This is the sharpest difference. On checking, Regulation E requires your written opt-in before the bank can charge you an overdraft fee for an ATM withdrawal or a one-time debit card purchase; if you have not opted in, those transactions are simply declined at no cost. Checks and recurring ACH payments are not covered by that opt-in rule and can still overdraw the account. Savings is rarely used for direct spending, so its usual role is the linked backup — an overdraft transfer from savings to checking, typically priced per transfer rather than as a flat overdraft fee.
Access and ATM network. Checking comes with a debit card and in-network ATM access; out-of-network withdrawals usually cost a fee from your bank plus a surcharge from the ATM owner. Savings often has no debit card at all, so cash access runs through a transfer to checking first, which can take one to three business days at an outside institution.
Transfer limits. Since the Federal Reserve's April 24, 2020 interim final rule amending Regulation D (12 C.F.R. 204), there is no federal six-per-month limit on convenient transfers from savings (RSM US LLP, 2020). Before that rule, moving money from savings to checking counted against the six (RSM US LLP, 2020). Some banks kept their own limit and fee anyway — the account agreement will say so.
Side-by-Side Comparison
| Criterion | Checking | Savings |
|---|---|---|
| Typical monthly maintenance fee | $0–$15, waived at a stated trigger such as one qualifying direct deposit per cycle or a named minimum daily balance | $0–$10, waived at a named minimum daily or average balance, usually lower than checking's |
| Typical minimum opening deposit | $0–$100 | $0–$100 |
| APY | Frequently 0.00%; rewards checking pays interest only if you meet a stated debit-transaction count and direct deposit each cycle | Variable APY disclosed under Truth in Savings (Reg DD); rate can change at any time |
| Day-to-day access | Yes — debit card, checks, bill pay, in-network ATMs | No debit card on most basic savings; access by transfer to checking, commonly 1–3 business days between institutions |
| Federal withdrawal cap | None | None since the Federal Reserve's April 24, 2020 interim final rule deleted Reg D's six-per-month limit (RSM US LLP, 2020); bank-imposed caps and per-item fees still allowed |
| Overdraft treatment | Reg E opt-in required before the bank charges you for an ATM or one-time debit card overdraft; checks and recurring ACH are outside that opt-in | Commonly declined; often the linked backup for an overdraft transfer priced per transfer |
| Deposit insurance | $250,000 per depositor, per institution, per ownership category at an FDIC bank (NerdWallet, undated); $250,000 for individual accounts at an NCUA credit union (NCUA, undated) | Same $250,000 limits, counted together with your other accounts in the same ownership category at that institution |
| Fund availability on deposits | Governed by Reg CC; exact business-day schedule is in the funds availability policy disclosure | Same Reg CC schedule applies |
Who Each Option Fits Best
- You get paid twice a month and your balance lands near zero before the next deposit. Checking, with the waiver tied to direct deposit rather than to a minimum balance. A balance-triggered waiver — say one that needs $1,500 held every day — will fail in the week before payday and cost you the monthly fee anyway. Decline Reg E overdraft coverage for debit and ATM transactions so those are declined at no fee instead of approved with one.
- You hold $5,000 or more that you have not touched in six months. Savings. In checking that balance earns 0.00% at most institutions; in savings it earns the disclosed variable APY. Keep enough in checking to clear your largest recurring bill and link the savings account for overdraft transfer, which is normally cheaper per event than an overdraft fee.
- You travel or move between states more than a few times a year. Checking, chosen on ATM network and out-of-network reimbursement rather than on APY. Ask the specific question: how many out-of-network ATM fees do you refund per statement cycle, and do you also refund the ATM owner's surcharge? Savings with no debit card gives you nothing at a cash machine abroad.
- You are holding more than $250,000 at one institution — a home sale, an inheritance, a business payout. Split it. Coverage is $250,000 per depositor, per institution, per ownership category (NerdWallet, undated), and checking plus savings in the same ownership category at the same bank are added together, not covered separately. At a credit union, individual accounts are insured to $250,000 and your interest in all joint accounts combined at that credit union is separately insured to $250,000 (NCUA, undated).
- You are saving toward a date 6 to 18 months out and keep raiding the fund. Savings at a different institution from your checking. The one-to-three-business-day external transfer is the friction, and the account may still carry a bank-imposed withdrawal cap even though the federal Reg D limit is gone (RSM US LLP, 2020).
Frequently asked questions
Is money safer in savings than in checking?
No — the insurance is identical. The FDIC insures up to $250,000 per depositor, per institution, per ownership category, covering deposit accounts such as checking and savings along with official items like cashier's checks and money orders (NerdWallet, undated). At a federally insured credit union, the NCUA's Share Insurance Fund insures individual accounts to $250,000, with IRA and Keogh retirement accounts protected separately up to $250,000, and the fund carries the full faith and credit of the United States (NCUA, undated). Your checking and savings in the same ownership category at one institution are added together against the single $250,000 limit.
Am I still limited to six withdrawals a month from savings?
Not by federal rule. On April 24, 2020 the Federal Reserve issued an interim final rule amending Regulation D (12 C.F.R. 204) to delete the six-per-month limit on convenient transfers and withdrawals from savings deposits, permitting an unlimited number (RSM US LLP, 2020). Before that change, a single savings-to-checking transfer used up one of the six (RSM US LLP, 2020). Banks and credit unions may still enforce their own cap and charge an excess-transaction fee per item, so read the account agreement section headed transaction limitations.
How long can the bank hold a check I deposit?
Availability is set by Regulation CC, and the schedule is measured in business days — days the bank is open, excluding weekends and federal holidays — not calendar days. Your institution must give you a funds availability policy disclosure that states the exact dollar amounts released first and the business-day count for the rest, plus the longer holds it may apply to new accounts, large deposits and repeated overdrafts. The same Reg CC schedule applies whether you deposit into checking or savings. Ask: when will the full amount of this specific check be available, in business days?
Someone made charges on my debit card. Is that the same as disputing a check?
No. Unauthorized electronic fund transfers — debit card purchases, ATM withdrawals, ACH debits from your checking account — fall under Regulation E, which sets an error-resolution process with reporting deadlines counted from the date the statement showing the problem was sent and limits your liability based on how fast you report. A check you wrote is not an electronic fund transfer; it is handled through your account agreement, a stop-payment order placed before the check clears, and state law on forged or altered items. Report debit card problems under Reg E in writing as well as by phone, and keep the date you reported.
Does it make sense to hold both a checking and a savings account?
That depends on your cash flow, not on any rule, but the mechanics favour it for two reasons. First, linking savings to checking lets the bank cover a shortfall by transfer, which is normally priced per transfer rather than as a per-item overdraft fee — check the fee schedule for both numbers. Second, the interest sits where it can accrue: standard checking frequently pays 0.00% APY while savings pays the variable APY on the Truth in Savings (Reg DD) disclosure. Holding both at the same institution does not increase your coverage, which stays at $250,000 per depositor, per institution, per ownership category (NerdWallet, undated).
Sources
- NerdWallet — What Is FDIC Insurance and What Are the Coverage Limits?
- NCUA — Share Insurance Fund Overview
Written by
Marisol Ferreira
Marisol untangles the daily noise of equities and bonds to find what actually moves portfolios. She writes with a skepticism toward consensus calls and a fondness for footnotes. Her beat is where macro theory meets messy reality.