Finance
What Is a Check Hold, and How Does It Work?
Deposited money you cannot spend yet has a release date set by federal rules — here is how to read a hold notice and work out when the funds land.
By Priya Chandrasekaran · Oct 06, 2026 · 6 min read
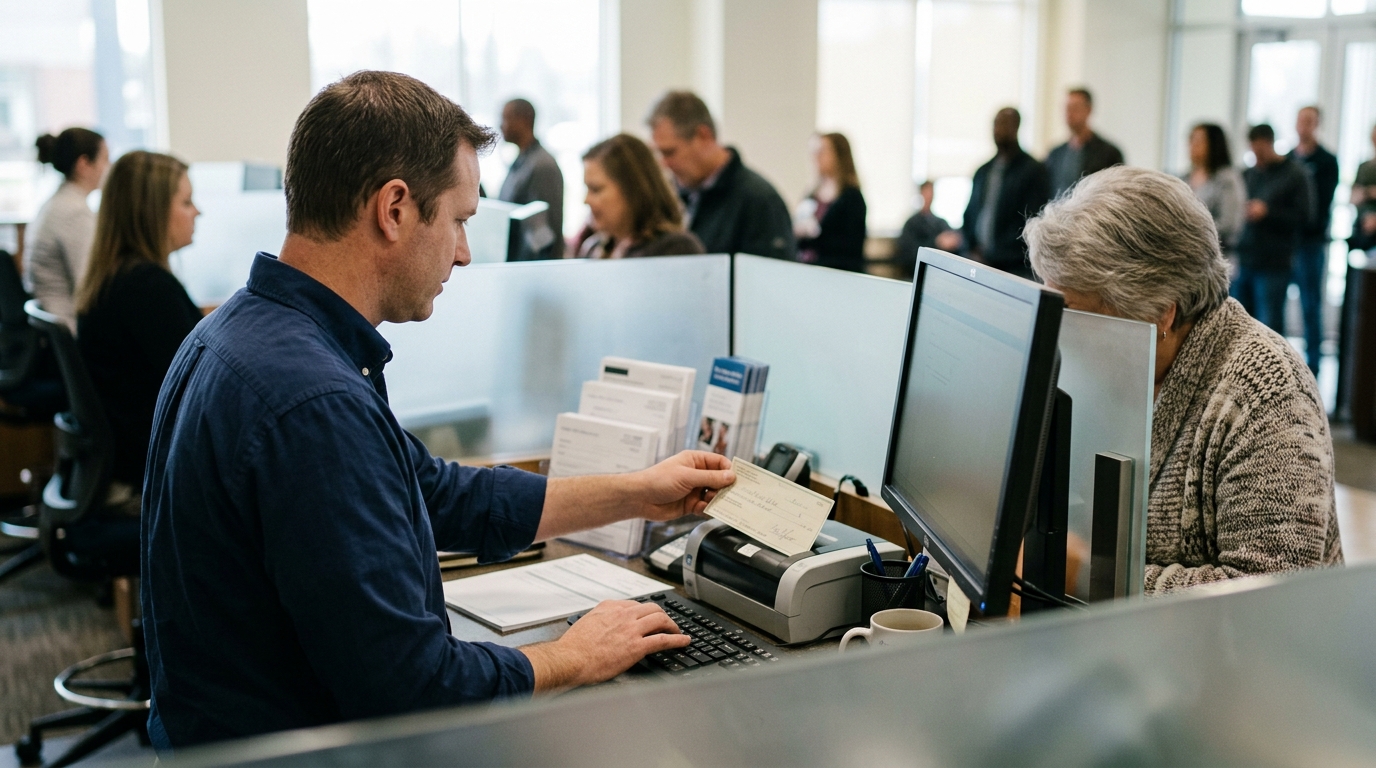
A check hold is the gap between the moment a bank credits a deposit to your balance and the moment you can actually spend it. Federal rules under Regulation CC set outside limits on that gap: most local check deposits into a checking account must be available no later than the second business day after the day of deposit (FDIC, 2024-03), with a smaller slice available the next business day.
The rules also let banks hold longer in named situations — new accounts, large deposits, repeated overdrafts — and each of those carries its own dollar trigger and its own written notice requirement.
What This Term Means
A check hold is a delay a bank places on part or all of a deposited check before you can withdraw the money or spend it. The deposit shows in your balance, but the "available" figure is lower — that difference is the hold.
The mechanism comes from Regulation CC, which implements the Expedited Funds Availability Act and the Check 21 Act. Credit unions are subject to the same funds-availability time schedules and disclosure requirements as banks (NCUA, undated), so a share draft account at a credit union works the same way as a checking account at a bank.
Reg CC's availability schedules are written for transaction accounts — checking and share draft accounts you can write checks against. Savings and money market deposit accounts sit outside those schedules, so a hold on a check deposited to savings runs on the institution's own policy, not the second-business-day rule.
Two things happen in parallel. Reg CC tells your bank when it must let you have the money. The separate collection process — your bank presenting the check to the paying bank — decides whether the check is actually good. Availability arriving first does not mean collection has finished. Under a permanent availability schedule in force since September 1990, local check deposits generally must be available no later than the second business day following the day of deposit (FDIC, 2024-03).
Business days exclude weekends and federal holidays, so a Friday afternoon deposit and a Monday morning deposit can land on the same release date.
Typical Amounts and Timeframes
| Deposit type or situation | When funds must be available |
|---|---|
| U.S. Treasury checks and on-us checks | Next business day, even if not deposited at a staffed teller station (FDIC, 2024-03) |
| First slice of other check deposits in one banking day | Lesser of $225 or the day's total, by the next business day; rises to $275 on July 1, 2025 (FDIC, 2024-03; CLA, 2025) |
| Remainder of a local check deposit | No later than the second business day after the banking day of deposit (FDIC, 2024-03) |
| Cashier's, certified, teller's checks, USPS money orders, state/local government checks not deposited at a staffed teller station | Second business day (FDIC, 2024-03) |
| Cash or checks at a nonproprietary ATM | No later than the fifth business day after the banking day of deposit (FDIC, 2024-03) |
| New account — first 30 calendar days from opening | First $5,525 of certain checks next business day; excess by the ninth business day (FDIC, 2024-03) |
| Large-deposit exception | Applies only to check deposits above $5,525 in one day; rises to $6,725 on July 1, 2025 (FDIC, 2024-03; CLA, 2025) |
| Repeated-overdrafts exception | Overdrawn on 6 or more banking days in the past 6 months, or 2 banking days at -$5,525 or worse (FDIC, 2024-03) |
| Extra time allowed on an exception hold | No more than 1 extra business day for on-us checks, 5 extra business days for local checks, unless a longer delay is shown reasonable (FDIC, 2024-03) |
| Cash-withdrawal threshold | $450, rising to $550 on July 1, 2025 (CLA, 2025) |
Where People Get This Wrong
"The hold expired, so the check cleared."
These are two different events. Reg CC's second-business-day rule (FDIC, 2024-03) governs when you may spend the money, not whether the paying bank honored the item. A check can be returned unpaid after you have already withdrawn the funds, and the deposit is then reversed against your balance.
"A long hold means my money is at risk."
Held funds are on deposit and insured the same as any other balance, up to the standard insurance limit of $250,000 per depositor, per insured bank, per ownership category at FDIC-insured banks and NCUA-insured credit unions. A hold is about access timing, not about the safety of the deposit.
"I can dispute a hold under Reg E."
Regulation E covers electronic fund transfers — debit card errors, ACH entries, ATM withdrawals — and sets error-resolution rights for those. A check hold is a Regulation CC funds-availability question. If the bank delays because it doubts a check is collectible, the reasonable-cause exception requires written notice of the basis for the hold at the time of deposit (FDIC, 2024-03).
"There must be a hard cap on new-account holds."
No regulatory time limit is set for how long a bank may hold local check deposits into a new account; only the $5,525 next-day slice and the ninth-business-day structure apply to the amounts the new-account exception covers (FDIC, 2024-03). The new-account window itself runs 30 calendar days from the date the account is established.
Frequently asked questions
Does the bank have to tell me in writing?
Yes, for most exception holds. The written general exception notice must state the account number, deposit date, amount delayed, the reason, and when the funds will be available (FDIC, 2024-03). Under the reasonable-cause exception, notice of the basis for the hold is required at the time of deposit.
Can a hold be extended because of a system outage?
Yes. Regulation CC lets banks suspend the normal availability schedule under emergency conditions — interruption of communications or computer facilities, suspension of payments by another bank, war, or other conditions beyond the bank's control (FDIC, 2024-03).
Why did a deposit at a different bank's ATM take longer?
Deposits of cash and checks at nonproprietary ATMs — machines your institution does not own or operate — must be available no later than the fifth business day following the banking day of deposit (FDIC, 2024-03), rather than the second business day for local checks at your own bank.
Do the dollar thresholds change?
Yes. Regulation CC's thresholds are adjusted for inflation every five years using the CPI-W. Effective July 1, 2025, the next-day availability minimum rises from $225 to $275 and the new-account, large-deposit and repeated-overdraft threshold rises from $5,525 to $6,725 (CLA, 2025). Check which figure applied on your deposit date.
Sources
- FDIC — VI-1 Expedited Funds Availability Act — Consumer Compliance Examination Manual (2024-03)
- CLA (CliftonLarsonAllen) — Regulation CC: What Financial Institutions Need to Know for July 2025 (2025)
Written by
Priya Chandrasekaran
Priya breaks down earnings calls, mergers, and balance sheets for readers who don't speak spreadsheet. She's most interested in how companies justify the numbers they report. Her columns favor clarity over jargon.