Finance
Should You Switch From a No-Fee Card to a Rewards Card?
An annual fee is a fixed cost you pay whether or not you earn, while interest on a carried balance is the number that decides if rewards survive at all.
By Renata Ibarra · Oct 06, 2026 · 9 min read
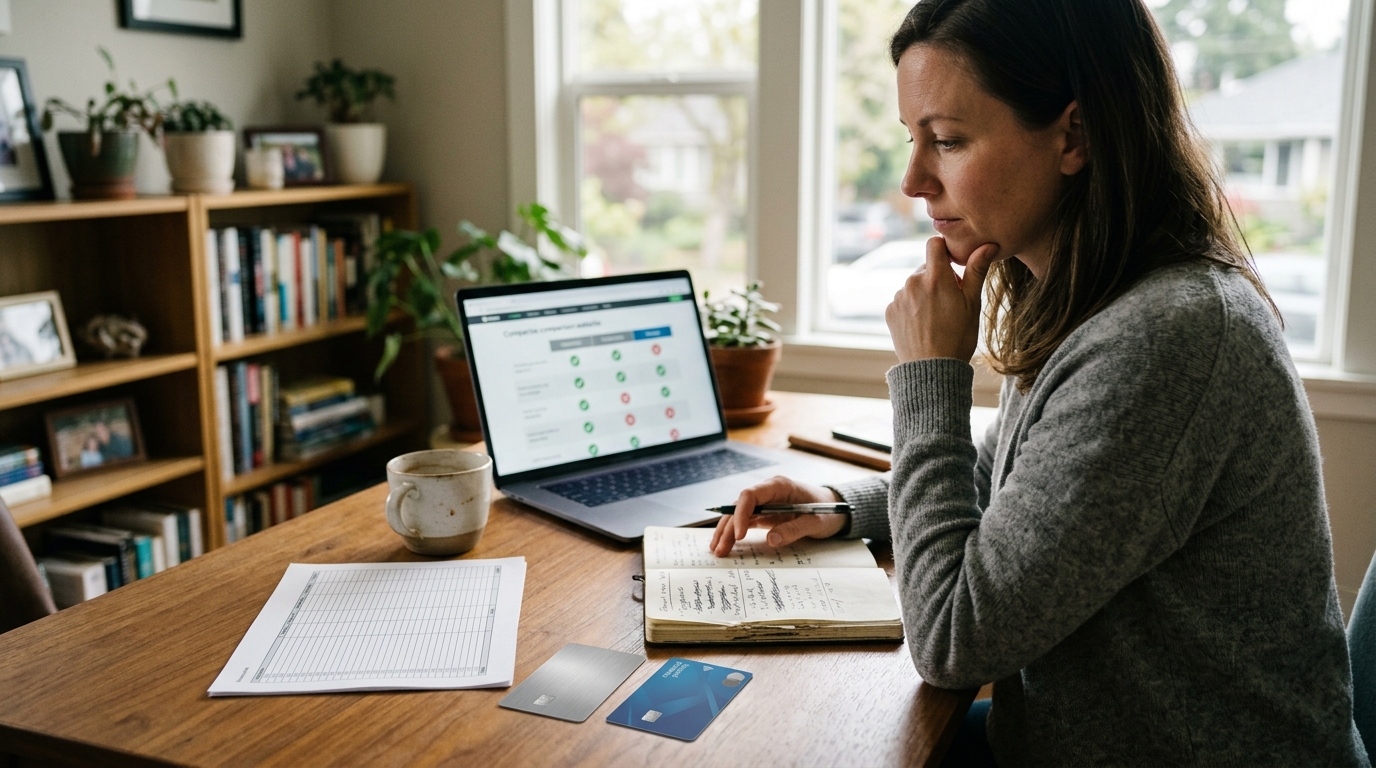
Switching from a no-fee card to a rewards card is a bet that what you earn will clear what you pay. There are only three inputs: the annual fee, your yearly spend times the rewards rate, and whatever interest you pay if a balance rolls over. Run those three numbers and the decision usually answers itself.
This guide compares the two card types line by line, works two spending scenarios with the arithmetic shown, and gives you a checklist for each side. Use bracketed placeholders for the actual offers in front of you — [No-Fee Card] and [Rewards Card] — and fill in their figures as you read.
Side-by-Side
Fill in your own two offers alongside the market figures below. Where an issuer does not publish a number, that is stated rather than guessed.
| Category | No-fee card | Rewards card that charges an annual fee |
|---|---|---|
| Annual fee | None — that is the defining feature | $94 to $157 on average among cards that charge one, depending on issuer size (CFPB survey data cited by Capital One); the average was $127, up from $62 in 2015 (CFPB Consumer Credit Card Market Report via CNBC Select, reported by PFCU) |
| Purchase APR | Average stated APR across all credit card accounts: 20.94% in Q2 2026 (LendingTree, from the Federal Reserve's G.19 release) | Average APR on a new card offer: 23.82% in Q2 2026; average on accounts assessed interest: 22.15% (same release) |
| Rewards structure | None, or the single flat rate your offer states — write it in | Tiered or points-based; about three in four general purpose accounts are now rewards cards, and about half of rewards earned sit on points products (CFPB, 2024-05) |
| Sign-up bonus | None unless your offer states one — treat it as $0 | The dollar or point figure and spend threshold printed on the offer page; rewards appeared on the front page of sampled offers 94% of the time, versus 78% for annual fees and 28% for APRs (CFPB, 2024-05) |
| Foreign transaction fee | Either none or 1% to 3% per transaction — Capital One states it charges none on its cards (Capital One) | Typically 1% to 3% of each qualifying transaction, most commonly around 3%, often split into roughly a 1% network fee plus a 1% to 2% issuing-bank fee (CreditCards.com) |
| Credit score needed | No published cutoff; issuer underwriting criteria are not public, so any score figure you see is an estimate | Also no published cutoff. CFPB-cited Federal Reserve research found near-prime and subprime cardholders typically pay more in interest and fees on a rewards card than on a card without rewards, even after counting the rewards earned (CFPB, 2024-05) |
| Rewards expiration | Nothing to expire if the card earns nothing | Most issuers with rewards programs have an expiration policy, most often triggered by account inactivity, defined inconsistently from issuer to issuer (CFPB, 2024-05) |
Two footnotes worth carrying into the next section. First, issuer size moves the APR: the 25 largest credit card issuers charged interest rates 8 to 10 percentage points higher than small and medium-sized banks and credit unions (CFPB, reported by PFCU). Second, if you compare your own score against anything, note which model you are looking at — a FICO 8 score and a VantageScore 3.0 score are built differently and are not interchangeable.
Where Each One Wins
Scenario one: $500 a month on groceries, paid in full every month.
Annual spend is $500 x 12 = $6,000. Say [No-Fee Card] pays a flat 1% with no annual fee, and [Rewards Card] pays 3% on groceries and charges the $127 average annual fee (CFPB via CNBC Select, reported by PFCU).
- No-fee card: $6,000 x 0.01 = $60 a year, minus $0 fee = $60 net.
- Rewards card at 3%: $6,000 x 0.03 = $180, minus $127 fee = $53 net.
- Rewards card at 2% instead: $6,000 x 0.02 = $120, minus $127 fee = -$7 net.
On these inputs the no-fee card returns $7 more than the 3% card and $67 more than the 2% card. The breakeven rate is the one where $6,000 x r - $127 = $60, which solves to r = 3.12%. So at $6,000 of annual spend against a 1% no-fee card and a $127 fee, the rewards card has to beat about 3.1% on all of that spend before it pulls ahead. If the rewards rate only applies to a grocery category and the rest of your spend earns 1%, recalculate using the split, not the headline rate.
A sign-up bonus changes year one only. An illustrative $200 bonus on the rewards card makes year one $180 + $200 - $127 = $253 against the no-fee card's $60. Year two drops back to $53. Check the spend threshold and the window on your own offer, and check the expiration terms — most issuers with rewards programs have an inactivity-based expiration policy (CFPB, 2024-05), and Americans earned $41.4 billion in credit card rewards in 2022 while leaving about $6 billion unredeemed (CFPB Credit Card Market Report as analyzed by The Motley Fool, reported by PFCU).
Scenario two: the same $6,000 of spend, but $2,000 of it rolls over unpaid all year.
Use the Q2 2026 average APR on a new card offer, 23.82% (LendingTree, from the Federal Reserve's G.19 release). Monthly periodic rate is 23.82% / 12 = 1.985%, so the first month's interest on $2,000 is $2,000 x 0.01985 = $39.70. Held flat for twelve months, that is $2,000 x 0.2382 = $476.40 in interest.
Compare that to the best case from scenario one: $180 in rewards minus the $127 fee is $53. The $476.40 in interest is roughly nine times the net rewards. Even the gap between the two averages matters: $2,000 at 23.82% is $476.40 versus $2,000 at the 20.94% all-accounts average, which is $418.80 — a $57.60 difference, larger than the entire $53 of net rewards.
This is not an edge case. Cardholders who revolve debt from one billing cycle to the next pay 94% of the total interest and fees charged on rewards cards but receive less than 30% of the rewards benefits distributed (CFPB, 2024-05).
Pick One or the Other
Stay with the no-fee card if:
- A balance rolls into the next cycle in most months — at 23.82% on a new card offer (LendingTree, Q2 2026), $2,000 held flat for a year costs $476.40, which no realistic rewards rate on $6,000 of spend recovers.
- Your annual card spend is under roughly $4,000, meaning even a 3% rate returns $120 against a $127 average annual fee.
- You want a long-dated account left open and untouched; a no-fee card costs nothing to keep, which protects your average account age and keeps the credit line in your utilization denominator.
- You rarely spend abroad, so the 1% to 3% foreign transaction fee range (CreditCards.com) is not a factor either way.
Move to the rewards card if:
- You pay the statement balance in full every month, so the 23.82% average new-offer APR never touches you and the fee-versus-rewards arithmetic is the whole decision.
- Your annual spend clears the breakeven — above about $4,250 at a 3% rate against a $127 fee, before counting any bonus.
- You can hit the bonus spend threshold on your offer with purchases you were making anyway, not purchases added to reach it.
- You travel internationally and the card charges no foreign transaction fee, against the 1% to 3% typical range (CreditCards.com) — Capital One, for example, states it charges none on its cards.
One thing to weigh before you apply: a new application adds a hard inquiry to your file and a new account lowers your average account age, both of which are inputs to scoring models such as FICO 8 and VantageScore 3.0. Whether any issuer approves you is not something you can read off a score — underwriting criteria are not public, so treat approval talk as an estimate.
Frequently asked questions
Does the annual fee come out of my rewards automatically?
No. The fee posts to your account as a charge you pay in cash, while rewards sit in a separate balance until you redeem them. That is why the arithmetic in scenario one subtracts the $127 average annual fee (CFPB via CNBC Select, reported by PFCU) from the rewards earned rather than netting them inside the program — and why unredeemed rewards are a real risk, with about $6 billion of the $41.4 billion earned in 2022 left unredeemed (CFPB Credit Card Market Report via The Motley Fool, reported by PFCU).
If I always pay in full, does the APR on the table matter at all?
If you never carry a balance past the grace period, the 23.82% average new-offer APR (LendingTree, Q2 2026) costs you nothing, and the decision collapses to the fee row against the rewards row. The caution is that the APR becomes the dominant number the moment one month goes unpaid: $2,000 at 23.82% for a year is $476.40, against $53 net from a 3% rate on $6,000 of spend less a $127 fee.
Should I close the no-fee card once I open the rewards card?
Closing it is a separate decision from switching. A no-fee card costs $0 a year to keep open, and leaving it open preserves its credit line in your utilization calculation and its age in your average account age — both scoring inputs. The one thing to watch is the rewards expiration row: most issuers with rewards programs expire points on account inactivity, defined inconsistently across issuers (CFPB, 2024-05), so an idle card may still need occasional use.
Sources
- Consumer Financial Protection Bureau — Credit Card Rewards (Issue Spotlight) (2024-05)
- PFCU — Credit Card Rewards Guide 2026
Written by
Renata Ibarra
Renata shapes the publication's voice and keeps its coverage honest when markets get loud. She edits with a focus on precision, especially around risk and uncertainty. She also writes occasional essays on how financial language shapes financial behavior.