Finance
Is a Retail Store Card's Welcome Discount Actually a Good Deal?
The discount hits once at the register; the APR stays on the account for years, so the answer turns on how many statement cycles you carry a balance.
By Marisol Ferreira · Oct 06, 2026 · 7 min read
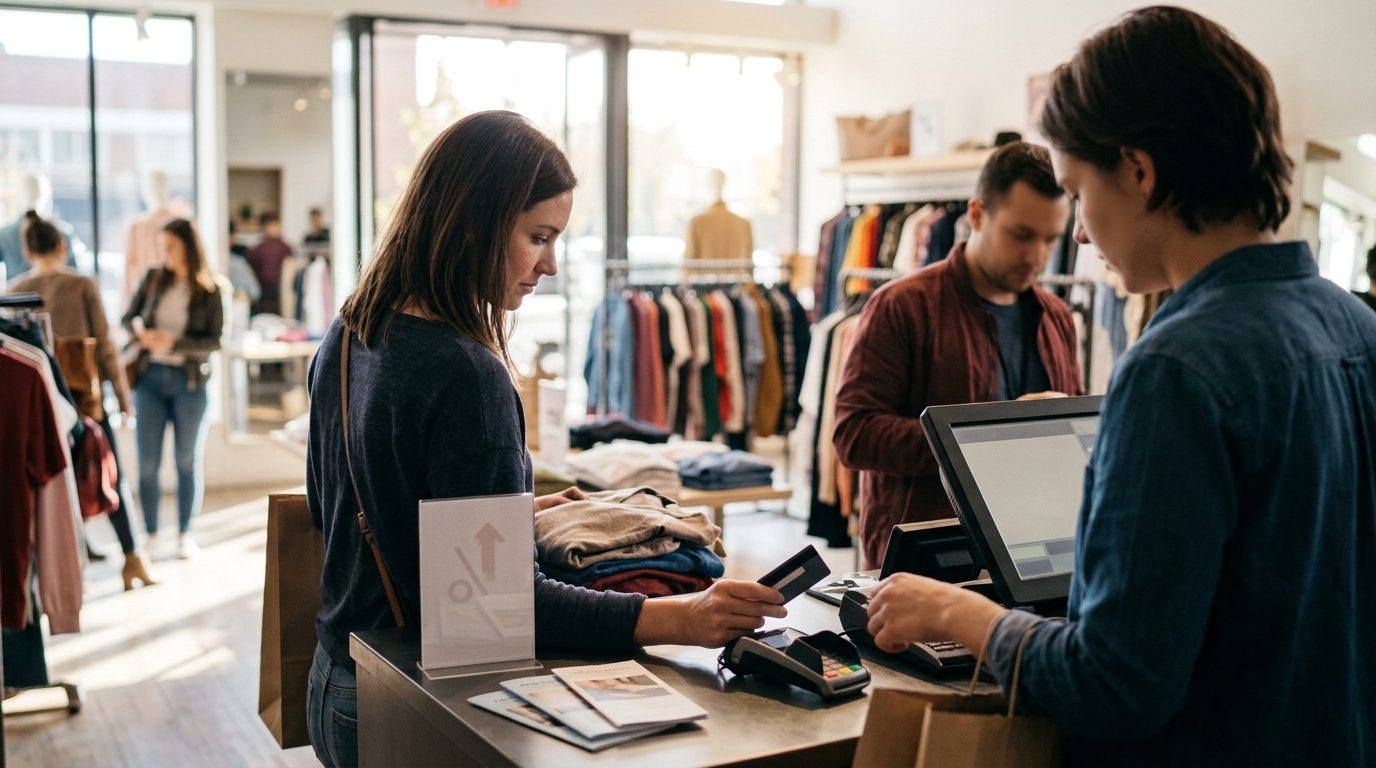
A store card's welcome discount is real money off today. What decides whether you keep it is what happens on the next few statements, because private label cards are priced near the top of the credit card market — the average purchase APR on cards from the largest U.S. retailers was 32.66% in December 2024 (Consumer Financial Protection Bureau, 2024-12).
This guide works the arithmetic both ways: what the discount is worth if you pay the first statement in full, and how many months of carrying a balance it takes before the interest eats it.
What This Actually Means
A retail store card's welcome discount is a one-time price cut — typically a percentage off or a dollar amount off — applied to your purchase at the moment you open a private label credit card. Private label means the card works only at that retailer or its family of brands, and the discount is a marketing cost the retailer accepts in exchange for putting a credit line on your name.
The discount is certain. The interest is not, and it is the larger number if you revolve. Here is the math on one purchase.
Say you buy $600 of goods and the card takes 15% off at the register. That is $600 × 0.15 = $90 saved, leaving a $510 balance on a brand new card. Use the December 2024 average private label purchase APR of 32.66% (Consumer Financial Protection Bureau, 2024-12). The monthly periodic rate is 32.66% ÷ 12 = 2.72%.
- Pay the $510 statement balance in full by the due date, and on most cards purchases are covered by a grace period, so interest is $0 and you keep the entire $90. Confirm the grace period terms in your own cardholder agreement, since they vary by issuer.
- Make no payments and let interest compound monthly for six months, and $510 grows to $510 × 1.0272^6 = $599.16. That is $89.16 in interest against a $90 discount. Six billing cycles, and you are level.
- Month seven onward, you are paying for the privilege of having taken the discount.
That break-even point is not an edge case. In 2023, 54% of private label card accounts carried a revolving balance, compared with 48% of general purpose cards, and early-stage delinquency ran at 17% on private label cards versus 13% on general purpose cards (Consumer Financial Protection Bureau, 2024-12).
The Numbers
Each row assumes no payments during the months shown and monthly compounding, so you can check it yourself: balance × (1 + APR ÷ 12)^months.
| Purchase & discount | Balance after discount | APR | Months carried | Interest | Net vs. paying cash |
|---|---|---|---|---|---|
| $600, 15% off = $90 | $510 | any | 0 — paid in full by due date | $0 | $90 ahead |
| $200, 20% off = $40 | $160 | 32.66% (2.72%/mo) | 3 | $13.42 | $26.58 ahead |
| $600, 15% off = $90 | $510 | 32.66% (2.72%/mo) | 6 | $89.16 | $0.84 ahead |
| $1,200, 10% off = $120 | $1,080 | 35.99% (3.00%/mo) | 12 | $459.67 | $339.67 behind |
The 32.66% figure is the December 2024 average for cards from the top U.S. retailers; 35.99% was the high end of a sampled range that ran down to 21.99%, with Academy Sports, Big Lots, Burlington, Camping World, Michaels and Petco cards issued by Bread Financial at 35.99% and J.C. Penney and American Eagle cards issued by Synchrony at 34.49% (Consumer Financial Protection Bureau, 2024-12). Your card's APR is on the statement and in the cardholder agreement — read it before you sign at the register, because 19% of retail cards had APRs above 35% (Consumer Financial Protection Bureau, 2024-12).
One more scenario does not fit a simple row, because the charge is retroactive. On a deferred interest plan, the CFPB worked through a $4,500 furniture purchase on a two-year promotion where the buyer paid down all but $180: at a 31.99% deferred interest APR, the charge was $1,439.55, despite $4,320 of the original balance already having been paid (Consumer Financial Protection Bureau, 2024-12).
Who This Affects Most
- You pay the full statement balance by the due date, every time. The $90 on a $600 purchase at 15% off stays $90, and at 32.66% you never see a finance charge. The discount is the whole transaction.
- You're financing a purchase over six to 12 months on a deferred interest promotion. Deferred interest means no interest only if the full promotional purchase is cleared inside the period; any remaining balance triggers interest back to the purchase date (Consumer Financial Protection Bureau, 2017). The CFPB has encouraged issuers to offer a true 0% promotion instead, because the back-end retroactive pricing is less transparent (Consumer Financial Protection Bureau, 2017).
- You already revolve a balance on another card and expect to revolve on this one. At 32.66%, a $510 balance left alone for six months costs $89.16 — so the welcome discount is spent by month six and you are paying out of pocket from month seven.
- You're applying for a mortgage or auto loan in the next few months. Opening the card adds a hard inquiry, which usually takes fewer than five points off a FICO Score and remains a factor for up to a year (Experian, 2024-11-08). The new account also lowers your average account age.
- You're offered a second card after being declined for the first one. One retailer's primary private label card carried a 28.99% APR while its "second look" card for riskier applicants carried 35.99% plus a $99 annual fee (Consumer Financial Protection Bureau, 2024-12). Those are two different products with the same logo on them.
Frequently asked questions
Does opening a store card at checkout change my credit score?
The application creates a hard inquiry, which usually takes fewer than five points off a FICO Score and stays relevant for up to a year (Experian, 2024-11-08). The new account also pulls down the average age of your accounts, while the added credit limit can lower your overall utilization ratio if you keep the balance low. Which effect dominates depends on your file and the scoring model being used.
Is a deferred interest offer the same as 0% APR?
No. With 0% APR, interest that would have accrued never existed; with deferred interest, it accrues from day one and is waived only if you clear the promotional balance inside the period, typically six to 12 months (Consumer Financial Protection Bureau, 2017). Leave $180 of a $4,500 purchase unpaid at a 31.99% deferred interest APR and the back charge in the CFPB's example was $1,439.55 (Consumer Financial Protection Bureau, 2024-12).
Will a better credit score get me a lower APR on a store card?
Usually not. Private label cards are more commonly priced with a single fixed APR for every cardholder regardless of credit score, unlike most general purpose cards, which set the APR by creditworthiness (Consumer Financial Protection Bureau, 2024-12). So a 760 FICO 8 applicant and a 640 FICO 8 applicant can be offered the same 32.66%-range rate.
Can the APR go up after I open the account?
Yes. Large retail card issuers raised APRs on existing cardholders and added paper statement fees during 2024 through change-of-term notices, and the CFPB noted a growing number of complaints about those paper statement fees (Consumer Financial Protection Bureau, 2024-12). Read change-of-term mailings rather than discarding them, and check your current rate on the statement, not on the sign at the register.
Sources
- Consumer Financial Protection Bureau — Issue Spotlight: The High Cost of Retail Credit Cards (2024-12)
- Consumer Financial Protection Bureau — Consumer Financial Protection Bureau Encourages Retail Credit Card Companies to Consider More Transparent Promotions (2017)
Written by
Marisol Ferreira
Marisol untangles the daily noise of equities and bonds to find what actually moves portfolios. She writes with a skepticism toward consensus calls and a fondness for footnotes. Her beat is where macro theory meets messy reality.