Finance
How to Close an Old Credit Card Without Losing Your Rewards
Redeem first, read the forfeiture clause, and work out what closing does to your utilization — the order you do these things in decides what you keep.
By Renata Ibarra · Oct 06, 2026 · 8 min read
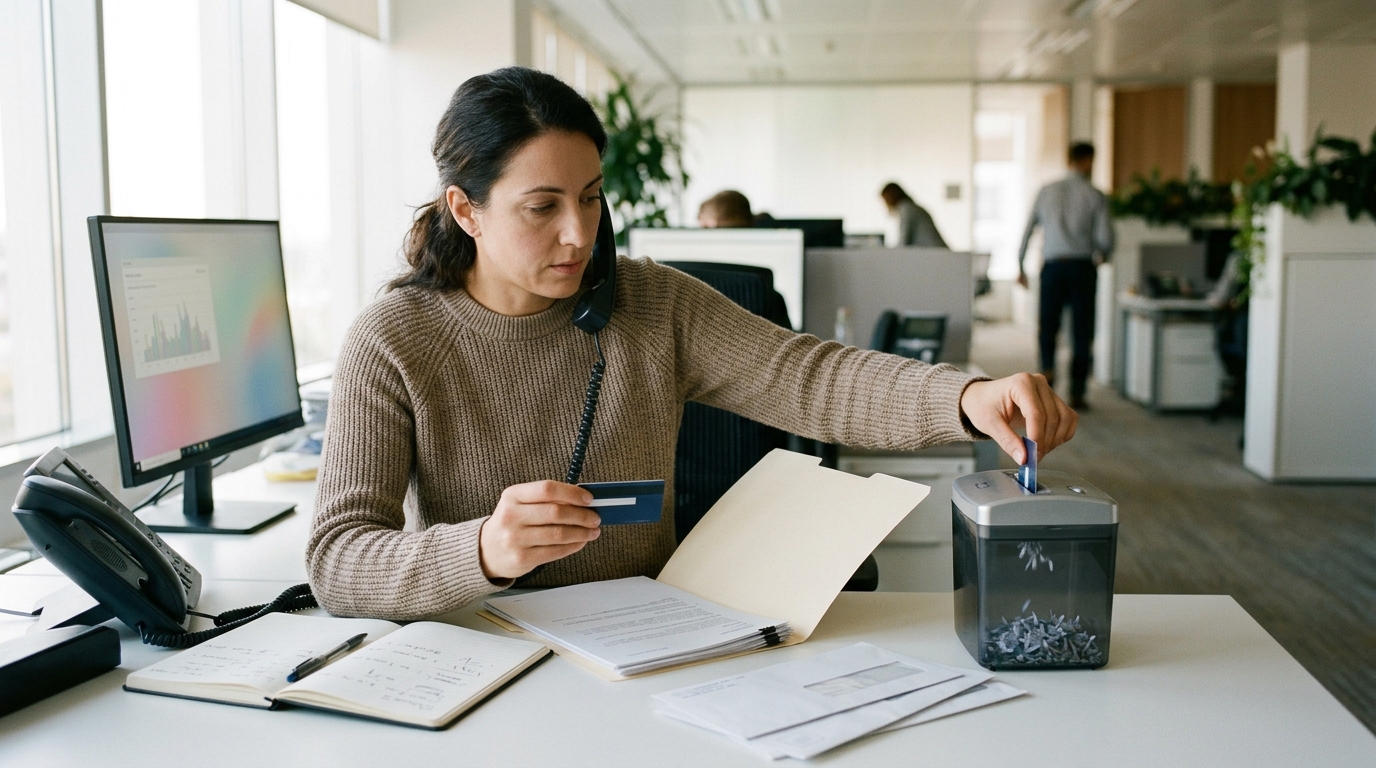
Closing a credit card you no longer use is a short administrative task, but the rewards balance sitting on it can disappear the moment the account is marked closed. Most programs treat points as the issuer's property, not yours, and some wipe them instantly.
This guide walks through the order of operations: read the terms, redeem or move the points, decide whether a product change does the job instead, zero the balance, then close in writing and confirm it.
Step by Step
- Open the rewards program terms and find the forfeiture clause. These are usually a separate document from the cardmember agreement, linked inside the issuer's app or online account. You are looking for the sentence describing what happens to unredeemed rewards when the account closes. Credit card companies can generally close an account without notice, and the terms of some rewards programs state that the consumer forfeits their rewards in that situation (Consumer Financial Protection Bureau, May 2024). The same report found that every quarter, four percent of accountholders loses access to at least some of their rewards.
- Check whether your state adds a grace period. Starting in December 2023, New York requires a 90-day grace period for the use of credit card reward points after notification of account closure or impending revocation (Consumer Financial Protection Bureau, May 2024). Terms can carry state-specific provisions: Wells Fargo's rewards terms include a New York provision stating that if the card tied to a rewards account is closed for any reason except fraud or misuse, Wells Fargo will issue a check for the cash equivalent of the available rewards balance (Consumer Financial Protection Bureau quoting Wells Fargo Rewards Program Terms and Conditions, May 2024). Rules differ by state and by issuer — read your own terms rather than assuming.
- Redeem, transfer or consolidate the balance. Do this before any closure request, through the rewards portal in the issuer app or website. Some programs let points survive closure if you hold another account with the same issuer — American Express cardholders can retain Membership Rewards points if they have another American Express card or checking account (U.S. News & World Report, undated). Whether yours allows that depends on the program.
- Call the issuer and ask about a product change before you ask to close. A product change typically keeps the same card number and account number and does not usually involve closing the current account or opening a new one (Capital One, March 2026). It typically does not trigger a hard inquiry and won't affect your credit scores if your credit limit stays the same (Capital One, March 2026). The trade-off: product changes may not be eligible for sign-up bonuses or introductory APR offers, and there is no guarantee that original benefits or rewards will transfer (Capital One, March 2026).
- Do the utilization arithmetic on paper. Add your balances and your total limits across all cards. If you owe $2,000 against $10,000 of combined limits, that is 20% utilization. Close a card carrying a $4,000 limit and the same $2,000 now sits against $6,000 of limits — 33%. Closing an existing credit card can increase your credit utilization ratio and lower your score (Consumer Financial Protection Bureau, December 2024). Those with the highest credit scores tend to have utilization ratios below 10%, and keeping it below 30% avoids a more substantial negative impact (Experian, undated).
- Clear the balance to zero and wait for one full billing cycle to close with a $0 statement. Cancel or re-point every recurring charge — subscriptions, insurance premiums, utility autopay — before that cycle ends.
- Request closure through a recorded channel. Use the secure message centre in the issuer app or a phone call, and ask for written confirmation of the closure date and a $0 balance. Keep it.
- Review the final statement line by line. Under the Fair Credit Billing Act, a dispute of a billing error must be made in writing and received by the creditor within 60 days after the first billing statement containing the error was sent (Capital One, undated). The letter must go to the creditor's designated billing-inquiries address, not the payment address, and telephone notice alone is not sufficient to trigger the Act's protections (Wikipedia, undated).
- Pull your credit reports a cycle or two later and confirm the account shows as closed in good standing with a $0 balance.
What You'll Need
- The full rewards program terms and conditions PDF for that specific card, including any state-specific addendum.
- Your current rewards balance in points or cash value, and the program's minimum redemption threshold.
- The 16-digit card number and the account number if they differ.
- Your current statement balance and your credit limit on that card, in dollars.
- The balances and credit limits of every other revolving account you hold, so you can calculate combined utilization before and after.
- A list of every recurring charge and autopay authorisation attached to the card.
- The issuer's designated billing-inquiries address, printed on the back of your statement — separate from the payment remittance address.
- The statement date of your most recent statement, which starts the 60-day Fair Credit Billing Act clock (Capital One, undated).
- Written confirmation of closure, once you have it, with the closure date.
What Can Go Wrong
The issuer closes the account before you redeem. Credit card companies can generally close an account without notice, and some rewards terms treat forfeiture as automatic on closure (Consumer Financial Protection Bureau, May 2024). Inactivity, a flagged transaction, or a routine portfolio review can all trigger this. The mechanism is contractual: the points are a liability on the issuer's books that the terms extinguish at closure, so there is nothing to appeal to once the account status flips. New York's 90-day grace period after notification exists precisely because of this gap (Consumer Financial Protection Bureau, May 2024) — other states may offer nothing equivalent.
A residual charge posts after you think the account is shut. A subscription billed on the old card, or interest accruing on a balance that was not actually zero on the statement date, can leave a small amount owing on a closed account. If no one is reading the statements, that becomes a missed payment, and payment history is the largest FICO Score category at 35% (myFICO, undated). If the charge is a billing error rather than yours, the written dispute must reach the creditor within 60 days of the first statement containing it; creditors must acknowledge the letter within 30 days and resolve it within two complete billing cycles, not to exceed 90 days (Capital One, undated). Miss the 60-day window and the Act's protections no longer apply.
Utilization jumps the month the limit disappears. Amounts owed is 30% of a FICO Score (myFICO, undated), and closing removes that card's limit from your total available credit while leaving the balances elsewhere untouched (Consumer Financial Protection Bureau, December 2024). The increase shows up on the next reporting cycle, not when you make the call, so people often connect it to the wrong event.
Frequently asked questions
Does closing an old card immediately shorten my credit history?
Not immediately. Closed credit card accounts in good standing may stay on your credit report for up to 10 years (U.S. News & World Report, undated), and negative information typically falls off seven years after the original date of delinquency while closed accounts in good standing fall off later (Chase, undated). Length of credit history is 15% of a FICO Score and looks at the age of your oldest account, the age of your newest account, and the average age of all accounts (myFICO, undated; Experian, undated). The near-term change after closure usually comes from utilization under the amounts owed category, not from account age.
Is a product change a way to keep the account open and still change cards?
It can be. A product change typically keeps the same card number and account number and does not usually involve closing the current account or opening a new one (Capital One, March 2026), and it typically does not trigger a hard inquiry and won't affect your credit scores if your credit limit stays the same (Capital One, March 2026) — so neither the new credit category (10% of a FICO Score, per myFICO, undated) nor your available credit moves. The cost is that product changes may not be eligible for sign-up bonuses or introductory APR offers, and there is no guarantee original benefits or rewards transfer (Capital One, March 2026). Whether your issuer offers one at all is a case-by-case underwriting decision, so treat any answer you get as an estimate.
If I keep the card open instead, what do I have to do?
Watch the statements. If you keep an unused account open, monitor statements to protect against identity theft and check for unexpected fees or charges (Consumer Financial Protection Bureau, December 2024). An annual fee posting on a card you never look at becomes a missed payment, and payment history is 35% of a FICO Score — the three-digit 300 to 850 number used by 90% of top lenders (myFICO, undated).
Sources
- myFICO (Fair Isaac Corporation) — How are FICO Scores Calculated?
- Consumer Financial Protection Bureau — Does it hurt my credit to close a credit card? (2024-12-31)
Written by
Renata Ibarra
Renata shapes the publication's voice and keeps its coverage honest when markets get loud. She edits with a focus on precision, especially around risk and uncertainty. She also writes occasional essays on how financial language shapes financial behavior.