Finance
Overdraft Fee, Explained: What It Costs and When It Applies
A charge for letting a payment through when your checking balance cannot cover it, plus the opt-in rule that decides whether debit swipes count.
By Tobias Lindqvist · Oct 06, 2026 · 6 min read
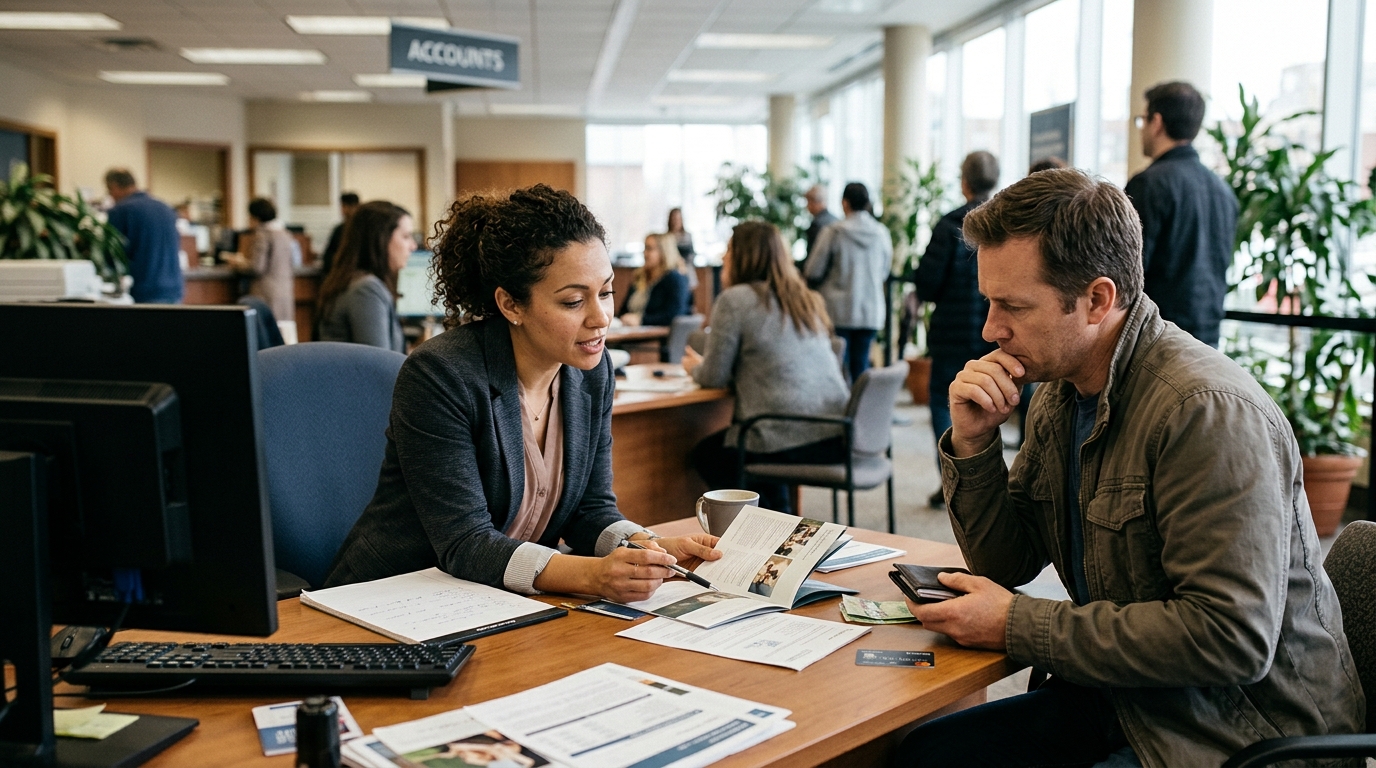
An overdraft fee is what a bank or credit union charges when it pays a transaction that drops your checking balance below zero. The median fee at institutions holding more than $10 billion in assets was $35 (Consumer Financial Protection Bureau, 2023-12), and most very large institutions still charge $35 per overdraft transaction (Consumer Financial Protection Bureau, 2024-12).
Whether you can be charged at all depends on the type of transaction. For one-time debit card and ATM transactions, you must have opted in first. For checks and ACH payments, no opt-in is required.
What This Term Means
An overdraft fee is a per-item charge your bank or credit union applies when it pays a transaction on your checking account even though the balance will not cover it. It is different from a non-sufficient funds (NSF) fee, which is charged when the institution returns or declines the item instead of paying it: the median overdraft fee was $35 and the median NSF fee $32 among institutions still charging them (Consumer Financial Protection Bureau, 2023-12).
The mechanism is discretionary. Your institution decides, item by item, whether to cover the shortfall. Regulation E, 12 CFR 1005.17(b), sets the limit on that discretion: an institution cannot assess an overdraft fee on a one-time debit card or ATM transaction without first obtaining your opt-in (Consumer Financial Protection Bureau, 2024-12). CFPB Circular 2024-05 goes further, stating that an institution violates the Electronic Fund Transfer Act and Regulation E if it has no proof it obtained that affirmative consent (Consumer Financial Protection Bureau, 2024-09). Recurring debit payments, paper checks and ACH debits sit outside that opt-in requirement, so those can overdraw and be charged whether you opted in or not.
Supervisory expectations come from the FDIC's Overdraft Payment Supervisory Guidance, FIL-81-2010, which covers automated overdraft payment programs (Federal Deposit Insurance Corporation, 2010-11-24). Later FDIC guidance addresses authorize-positive, settle-negative fees, where a transaction was approved against a positive balance but settled against a negative one (Federal Deposit Insurance Corporation, 2023).
Overdraft fees attach to checking accounts. A savings account linked as overdraft protection is usually charged a separate, smaller transfer fee instead, so check your fee schedule for the transfer line, not the overdraft line.
Typical Amounts and Timeframes
| Item | Number to expect |
|---|---|
| Median overdraft fee, institutions over $10 billion in assets (CFPB, 2023-12) | $35 per item |
| Per-transaction fee at most very large institutions (CFPB, 2024-12) | $35 |
| Average overdraft fee across checking accounts surveyed (Bankrate 2023 survey, cited by CFPB, 2023-12) | $26.61 |
| Median NSF fee where still charged (CFPB, 2023-12) | $32 per returned item |
| Institutions that dropped the fee while still covering overdrafts (National Consumer Law Center, 2025) | $0 |
| Fee options under the December 2024 rule, since repealed (CNBC, 2024-12-12) | $5, or a cost-based amount |
| Annual cost to a household with more than 10 overdrafts (CFPB, 2023-12) | at least $385 |
| Total paid by US consumers each year (National Consumer Law Center, undated) | about $9 billion |
| Check deposit: amount available next business day under Reg CC, threshold rising from $225 (CLA, 2025) | first $275 |
| New accounts: next-day threshold, rising from $5,525 (CLA, 2025) | $6,725 |
| Standard full check availability, Reg CC 229.13 exceptions aside | by the 3rd business day after deposit |
| Cash or check deposited at a non-proprietary ATM, Reg CC 229.12(f) | by the 5th business day after the banking day of deposit |
All hold periods above are business days, not calendar days. Weekends and federal holidays do not count, so a Friday deposit with a third-business-day release can mean Wednesday.
Where People Get This Wrong
"I never opted in, so I can't be overdrawn at all."
Opting out under Regulation E, 12 CFR 1005.17(b), only stops fees on one-time debit card and ATM transactions. Checks, ACH debits and recurring card payments on your checking account can still overdraw it and still carry the fee, which runs to a median of $35 at large institutions (Consumer Financial Protection Bureau, 2023-12).
"Overdraft fees are capped at $5 now."
They are not. The CFPB finalized that rule in December 2024, and a Congressional Review Act resolution nullifying it was signed in 2025 (California Credit Unions, 2025-05-09). The House voted 217-211 to overturn it (Banking Dive, 2025-04-10) and the Senate 52-48 (National Consumer Law Center, 2025). No federal dollar cap replaced it.
"My balance was positive when I swiped, so the fee is a mistake."
It may be a compliance problem, but it is not automatically reversible. FDIC guidance addresses authorize-positive, settle-negative fees, where the transaction was authorized against a positive balance and settled days later against a negative one (Federal Deposit Insurance Corporation, 2023). Ask for the authorization date, the settlement date and the balance on each.
"I deposited a check that morning, so the money was there."
Deposit timing is governed by Regulation CC, not by what your app displays. Only the first $275 of certain check deposits must be available the next business day, with the threshold rising from $225 (CLA, 2025), and a deposit at a non-proprietary ATM need not be available until the fifth business day (America's Credit Unions, undated).
"One bad day means one fee."
Fees are charged per item. A household with more than 10 overdrafts in a year faced at least $385 at the $35 median (Consumer Financial Protection Bureau, 2023-12).
Frequently asked questions
Can I be charged for a debit card overdraft I never agreed to?
Regulation E, 12 CFR 1005.17(b), requires your affirmative opt-in before any overdraft fee on a one-time debit card or ATM transaction (Consumer Financial Protection Bureau, 2024-12). CFPB Circular 2024-05 states that charging without proof of that consent violates the Electronic Fund Transfer Act (Consumer Financial Protection Bureau, 2024-09).
What is the difference between an overdraft fee and an NSF fee?
An overdraft fee means the item was paid and your checking balance went negative; the median was $35. An NSF fee means the item was returned unpaid; the median was $32 among institutions still charging one (Consumer Financial Protection Bureau, 2023-12). A returned check can also trigger a separate fee from the payee.
Do all banks and credit unions charge overdraft fees?
No. Some large institutions have eliminated the fee entirely while still covering overdrafts (National Consumer Law Center, 2025). Even so, consumers pay about $9 billion a year in overdraft fees overall (National Consumer Law Center, undated). Compare fee schedules line by line before you open a checking account.
If I dispute an overdraft fee, does Regulation E protect me?
Regulation E error-resolution rights cover electronic fund transfers, such as debit card and ATM transactions, including fees charged without the opt-in required by 12 CFR 1005.17(b). Paper check and ACH disputes follow different rules. Ask which process your institution is applying and request the authorization and settlement dates for each item.
Sources
- Consumer Financial Protection Bureau — Overdraft Lending: Very Large Financial Institutions (final rule) (2024-12)
- Consumer Financial Protection Bureau — CFPB Takes Action to Stop Banks from Harvesting Overdraft Fees Without Consumers' Consent (2024-09)
Written by
Tobias Lindqvist
Tobias tracks central banks, currencies, and the slow-moving forces behind interest rates. He's skeptical of easy narratives and prefers to follow the data where it leads. His writing often zooms out when everyone else zooms in.