Finance
Balance Transfer Card or Personal Loan: Comparing the Real Cost
Two ways to clear one balance: a fee you pay once against interest you pay monthly — and the arithmetic that shows which one costs you less.
By Desmond Okafor · Oct 07, 2026 · 8 min read
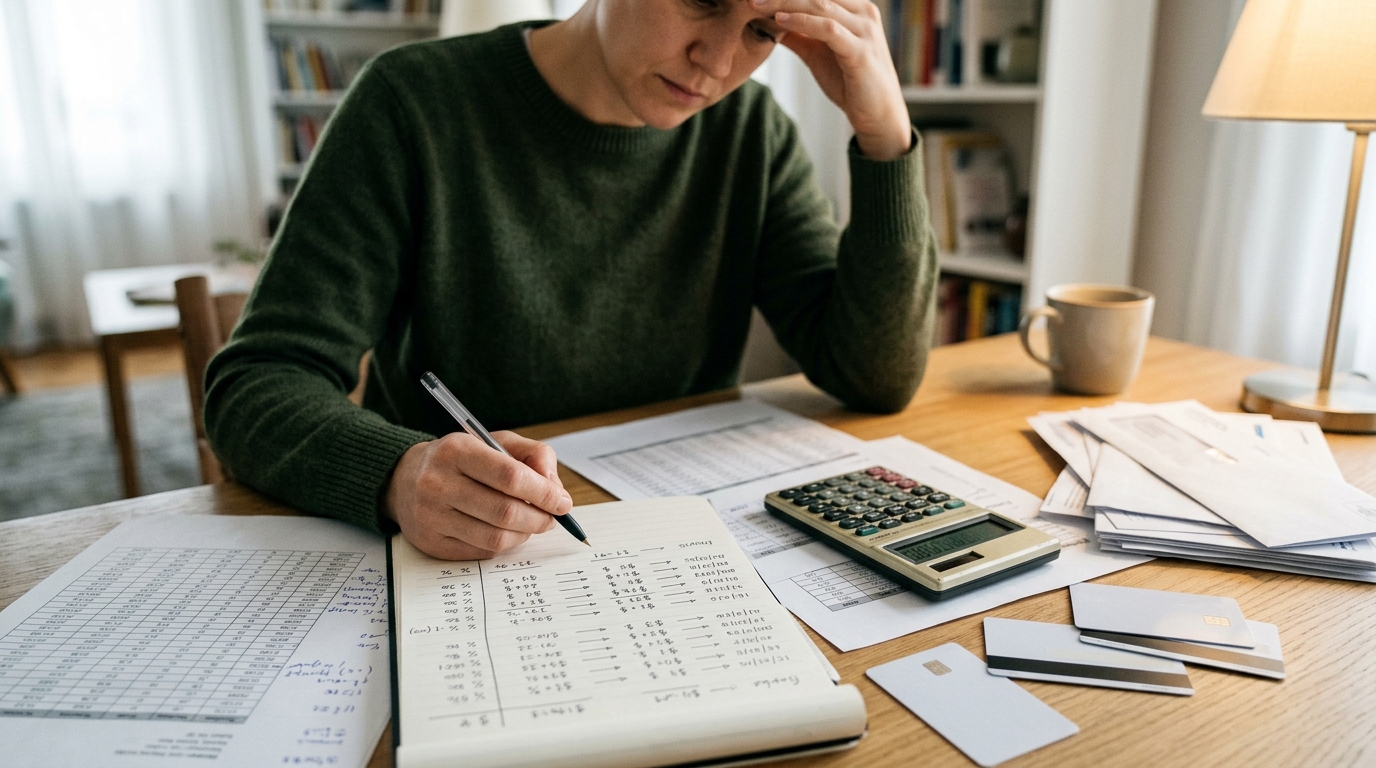
A balance transfer card and a fixed-rate personal loan both move expensive credit card debt somewhere cheaper. They charge for it differently: the card usually takes a one-off fee up front and gives you a promotional rate for a limited window, while the loan charges interest every month for a fixed term. Which costs less depends on your balance, the monthly payment you can actually make, and whether you clear the debt before the promotional window closes.
Every number below that is not sourced is an assumption, labelled as one. Your own figures come from the card's rate and fee table, the loan's disclosure, and — for market averages — the Federal Reserve's G.19 release.
Side-by-Side
Neither product is a single offer, so the cells below name the figure and where you read it today rather than quoting a rate that will have moved by the time you apply.
| Category | Balance transfer card | Personal loan |
|---|---|---|
| Annual fee | None on many transfer-focused cards; if there is one, it is printed in the card's fee table before you accept. | None on unsecured personal loans; the equivalent charge is an origination fee, shown in the loan disclosure. |
| Up-front cost to move the balance | A balance transfer fee, usually a percentage of the amount transferred or a fixed amount, whichever is more (Consumer Financial Protection Bureau, 2022-12-28). It can be charged even on a 0% offer (CFPB, 2024-09-25). | None as a transfer fee; an origination fee, if charged, is deducted from or added to the amount you borrow. |
| APR | A promotional rate for a limited time, after which the rate may rise and the required payment with it (CFPB, 2022-12-28). For market context, the Federal Reserve's G.19 release reports credit card APR for "all accounts" and for "accounts assessed interest" (Federal Reserve, 2025). | Fixed for the term on most bank loans. The G.19 release reports the commercial bank interest rate on 24-month personal loans (Federal Reserve, 2025). |
| Rewards structure | None on the transferred balance — transfers do not earn points or cash back on standard terms. Read the rewards terms if the card also earns on purchases. | None. A loan is not a spending account. |
| Sign-up bonus | None for transferring. Where a bonus exists it is tied to purchase spending in an opening window, not to transfers; check the offer terms. | None. |
| Foreign transaction fee | None on cards that advertise no foreign transaction fee; otherwise a percentage per transaction, listed in the fee table. Irrelevant to the transferred balance either way. | None — there are no transactions to charge. |
| Credit score needed | No published cutoff. Issuers do not disclose underwriting rules, so any approval odds you are shown are an estimate. Ask which model is pulled — FICO 8 and VantageScore 3.0 are both common, and one file can score differently in each. | No published cutoff, same caveat. Lenders often disclose a soft-pull pre-qualification before the hard inquiry. |
| Timing | G.19 figures for context are generally issued on the fifth business day of each month (Federal Reserve, 2025). | Same source, same release. |
Where Each One Wins
Scenario one: $6,000 balance, and you can pay about $345 a month.
Transfer card. Assume a 3% transfer fee and an 18-month 0% promotional window. The fee is 0.03 × $6,000 = $180, added to the balance, so you owe $6,180. Split across 18 months: $6,180 ÷ 18 = $343.33 a month. If every payment lands, the total cost of the debt is the $180 fee. Nothing else.
Personal loan. Assume $6,000 over 24 months at a fixed 12% APR. The monthly rate is 0.12 ÷ 12 = 1%. The payment works out at $282.45 a month; 24 × $282.45 = $6,778.80, so the interest is $778.80.
At those assumed figures the card costs $180 and the loan costs $778.80 — a $598.80 gap, driven entirely by the fee being charged once while the loan's 12% runs for 24 months. The card wins on cost here, but only because the whole $6,180 clears inside the 18 months. Miss that, and the leftover sits at the go-to APR.
Scenario two: $12,000 balance, and $300 a month is the most you can find.
Transfer card. A 3% fee on $12,000 is $360, so you start at $12,360. Eighteen months at $300 pays $5,400, leaving $6,960 when the promotional rate ends. Assume the go-to APR is then 24.99%: the first month's interest is $6,960 × 0.2499 ÷ 12 = $144.94, so of that $300 payment only $155.06 touches the principal. Continuing at $300 a month clears the rest in about 32 further months, roughly 32 × $300 = $9,600 paid against $6,960 of principal — about $2,640 in interest, plus the $360 fee. Call it $3,000, over about 50 months.
Personal loan. Assume $12,000 over 60 months at a fixed 13% APR. The monthly rate is 13 ÷ 12 = 1.0833%, the payment is $273.05, and 60 × $273.05 = $16,383 — about $4,383 in interest.
On those assumptions the card path costs around $3,000 against the loan's $4,383, so the card is cheaper by roughly $1,383. The arithmetic is sensitive, though: at a 29.99% go-to APR the same leftover $6,960 costs $6,960 × 0.2999 ÷ 12 = $173.94 in the first month and about $3,540 in total interest, narrowing the gap to a few hundred dollars. And the card figure assumes you never go more than 60 days late — past that point the issuer may raise the rate on all balances on the account, including the transferred one (Consumer Financial Protection Bureau, 2022-12-28). The loan's $273.05 does not move. What you are buying with the extra interest is a payment that cannot be repriced and an end date you can see.
Pick One or the Other
Lean balance transfer card if:
- You can divide the balance plus the fee by the number of promotional months and pay that figure every month — $6,180 ÷ 18 = $343.33 in the first scenario — without needing the card for new spending.
- Your balance is small enough that a one-off percentage fee is less than a year or two of loan interest, as the $180 fee versus $778.80 comparison shows.
- You are not planning another credit application soon, so the hard inquiry from the transfer application and the new account's effect on your average account age have time to age before anything else is scored.
- You will leave the old card open after the transfer, so your total available credit — and therefore your utilization ratio — does not drop the moment the balance moves.
Lean personal loan if:
- The payment you can actually afford would still leave a balance when the promotional window ends, as the $6,960 leftover in scenario two does.
- A variable rate is a problem for you: you want one figure, like $273.05, for the whole term, with no repricing trigger if a payment slips past 60 days.
- You have been near the limit on the card you are paying off and want the debt off a revolving line entirely, since instalment balances are not counted in revolving utilization.
- You need the debt consolidated from more than one card into a single payment and a single payoff date, rather than managing a promotional end date.
Frequently asked questions
Is a 0% transfer offer actually free?
No. The table's up-front cost row is the reason: the balance transfer fee is usually a percentage of the amount transferred or a fixed amount, whichever is more (Consumer Financial Protection Bureau, 2022-12-28), and the issuer is permitted to charge it even on a zero percent rate offer (CFPB, 2024-09-25). On the $6,000 balance above, a 3% fee is $180 — that is the price of the 0% window, not an add-on you can decline.
Will the transfer earn me rewards or a sign-up bonus?
Treat both as none, as the table shows. Transferred balances do not earn points or cash back on standard terms, and where a card advertises a sign-up bonus it is normally tied to purchase spending in an opening window rather than to a transfer. If a card is worth taking for its bonus, judge that separately from the transfer arithmetic.
What score do I need, and what does applying do to mine?
The table's credit score row says no published cutoff for either product, because issuers and lenders do not disclose underwriting criteria — any approval odds shown to you are an estimate. Ask which model is being pulled, since FICO 8 and VantageScore 3.0 can report different numbers from the same file. Mechanically, the application itself adds a hard inquiry and a new account lowers your average account age; moving card debt to a loan takes that balance out of revolving utilization, while closing the old card after a transfer removes its limit from your available credit and raises utilization on what remains.
Sources
- Consumer Financial Protection Bureau — Credit cards key terms (2022-12-28)
- Consumer Financial Protection Bureau — What is a balance transfer fee? Can a balance transfer fee be charged on a zero percent interest rate offer? (2024-09-25)
Written by
Desmond Okafor
Desmond covers personal finance with an eye for the small decisions that compound into big outcomes. He's drawn to budgeting tools, debt payoff strategies, and the psychology behind spending. He writes for readers who feel behind and want a clear next step.