Finance
Traditional IRA vs. Roth IRA: Which One Saves You More
The 2025 income limits, the forms each one needs, and the point where a deduction you cannot take ends up making the choice for you.
By Desmond Okafor · Oct 06, 2026 · 10 min read
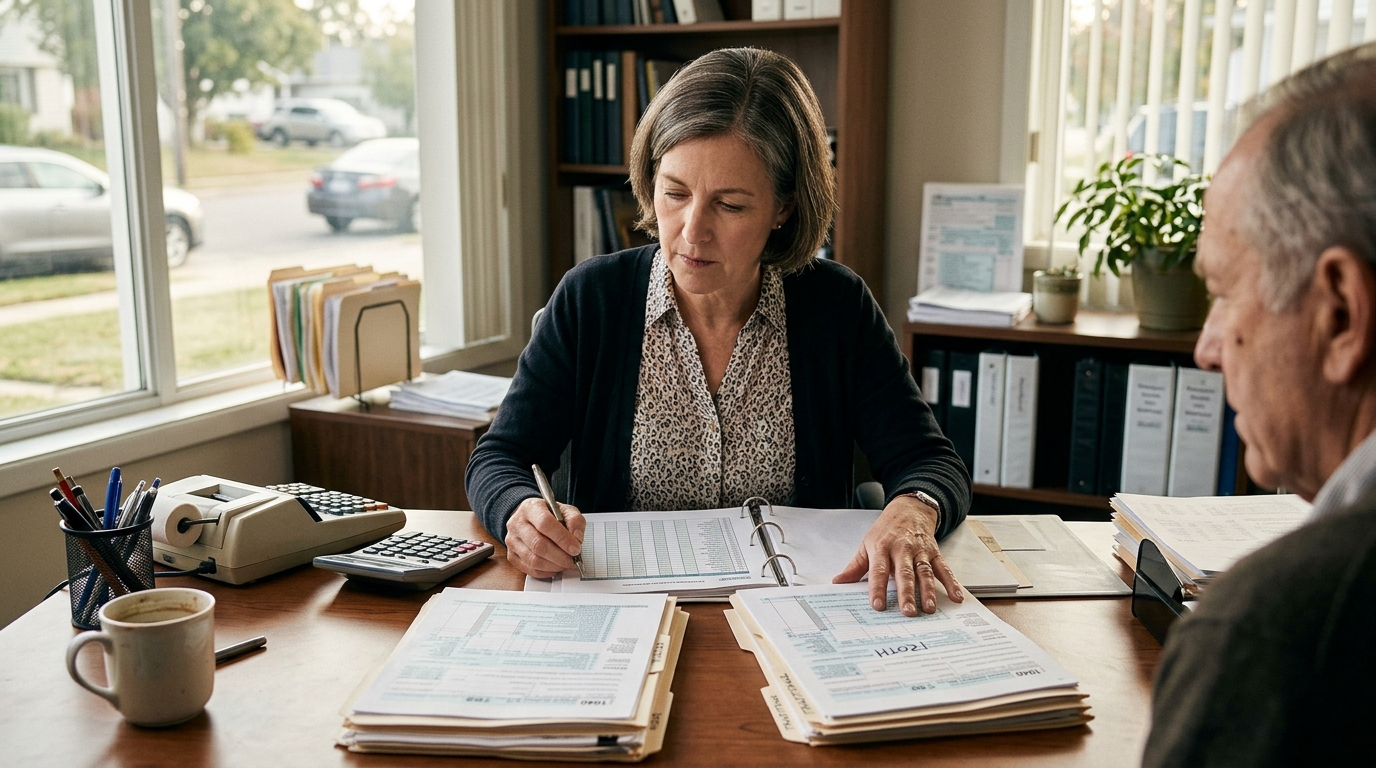
A traditional IRA and a Roth IRA take the same maximum contribution in 2025 — $7,000, or $8,000 if you are age 50 or older (Internal Revenue Service, 2025). The difference is when the tax break lands: the traditional version may cut this year's taxable income, while the Roth never does, because contributions to a Roth IRA are never deductible (Internal Revenue Service, 2025).
So the decision turns on two numbers you already have — your modified adjusted gross income and your filing status — plus one yes/no question: are you or your spouse covered by a retirement plan at work? This guide walks those numbers through the 2025 thresholds.
The Two Options, Side by Side
All figures below are for the 2025 tax year.
| Criterion (2025) | Traditional IRA | Roth IRA |
|---|---|---|
| Contribution limit, under age 50 | $7,000 (Internal Revenue Service, 2025) | $7,000 (Internal Revenue Service, 2025) |
| Contribution limit, age 50 or older | $8,000 (Internal Revenue Service, 2025) | $8,000 (Internal Revenue Service, 2025) |
| Deduction on this year's return | Up to $7,000 or $8,000, subject to the limits below | $0 — Roth contributions are never deductible (Internal Revenue Service, 2025) |
| Deduction if neither spouse is covered at work | Lesser of $7,000 ($8,000 if 50+) or 100% of compensation, no income phase-out (Internal Revenue Service, 2025) | $0 |
| Deduction phase-out, covered at work, single or head of household | Full at $79,000 or less, partial $79,000–$89,000, none at $89,000 (Internal Revenue Service, 2025) | $0 at every income |
| Deduction phase-out, covered at work, married filing jointly | Full at $126,000 or less, partial $126,000–$146,000, none at $146,000 (Internal Revenue Service, 2025) | $0 at every income |
| Deduction phase-out, only your spouse is covered, filing jointly | Full at $236,000 or less, partial $236,000–$246,000, none at $246,000 (Internal Revenue Service, 2025) | $0 at every income |
| Deduction, married filing separately, covered at work | Partial below $10,000 of modified AGI, none at $10,000 or more (Internal Revenue Service, 2025) | $0 at every income |
| Income ceiling to contribute at all, single or head of household | Contributions still permitted above the deduction limits; the nondeductible part goes on Form 8606 | Full contribution below $150,000, reduced $150,000–$165,000, none at $165,000 (Internal Revenue Service, 2025) |
| Income ceiling to contribute, married filing jointly | Same as above — nondeductible contributions reported on Form 8606 | Full below $236,000, reduced $236,000–$246,000, none at $246,000 (Internal Revenue Service, 2025) |
| Income ceiling, married filing separately and lived with spouse | Partial deduction only below $10,000 | Reduced from more than $0, none at $10,000 or more (Internal Revenue Service, 2025) |
| Effect on AGI, and so on refund or balance due | Deductible amount cuts AGI by up to $7,000 or $8,000 | AGI changes by $0 |
| Form required | Form 8606, Nondeductible IRAs, only if you make nondeductible contributions (Internal Revenue Service, 2025) | No form required just to contribute (Internal Revenue Service, 2025) |
| Counts for the Saver's Credit | Yes — up to $2,000 per person counted, at a rate of 10% to 50% (Internal Revenue Service, 2025) | Yes — same $2,000 cap and 10%–50% rate |
| Required minimum distributions | Begin in the year you turn 73 (Internal Revenue Service, undated) | None required (Internal Revenue Service, undated) |
| Distribution before age 59½ | Includible in taxable income and may carry a 10% additional tax, with listed exceptions (Internal Revenue Service, undated) | Roth distribution ordering rules differ; check the IRS rules for your account before withdrawing |
How to Tell Which One Applies to You
Work through these in order with your own 2025 figures.
- Write down your filing status and modified AGI. Everything below keys off those two. Married filing separately is the harshest status here: if you lived with your spouse at any point in the year, the Roth contribution is reduced from more than $0 of modified AGI and is gone at $10,000 (Internal Revenue Service, 2025).
- Answer whether you — or your spouse — are covered by a retirement plan at work. If neither of you was covered for any part of the year, your traditional deduction is the lesser of $7,000 ($8,000 at age 50 or older) or 100% of your compensation, with no income phase-out at all (Internal Revenue Service, 2025). Stop here: a full deduction is on the table at any income.
- If you are covered, find your deduction band. Single or head of household: full at $79,000 or less, partial to $89,000, none at $89,000 (Internal Revenue Service, 2025). Married filing jointly: full at $126,000 or less, partial to $146,000, none at $146,000 (Internal Revenue Service, 2025). If only your spouse is covered: full at $236,000 or less, none at $246,000 (Internal Revenue Service, 2025).
- Now test Roth eligibility. Single or head of household: full contribution below $150,000, reduced to $165,000, none at or above $165,000 (Internal Revenue Service, 2025). Married filing jointly: full below $236,000, none at $246,000 (Internal Revenue Service, 2025).
- Check the Saver's Credit caps, because a deduction can move you under one. For 2025, AGI must not exceed $79,000 (married filing jointly), $59,250 (head of household), or $39,500 (single, married filing separately, or qualifying surviving spouse) (Internal Revenue Service, 2025). The credit is 10% to 50% of up to $2,000 per person, figured on Form 8880, Credit for Qualified Retirement Savings Contributions, and reported on Schedule 3 (Form 1040), line 4 (Internal Revenue Service, 2025).
- Land on an answer. Deduction of $0 and Roth available: the Roth is the only one of the two producing a tax result. Deduction available and your AGI is within a few thousand dollars of the $79,000 / $59,250 / $39,500 Saver's Credit caps: the traditional deduction buys both the deduction and the credit. Deduction available but AGI far below those caps: you are weighing today's rate against a later one, plus required minimum distributions starting at 73 on the traditional versus none on the Roth (Internal Revenue Service, undated).
- If both doors are shut — say, married filing jointly at $250,000 with workplace coverage — the remaining move is a nondeductible traditional contribution of up to $7,000 or $8,000, which requires Form 8606 (Internal Revenue Service, 2025).
Worked Example
Dana files as head of household for 2025, is 45, and is covered by a retirement plan at work. Her AGI before any IRA contribution is $64,000. She has $7,000 to put somewhere.
Traditional IRA. Her modified AGI of $64,000 is below $79,000, so she gets the full deduction (Internal Revenue Service, 2025). AGI becomes $64,000 − $7,000 = $57,000. The head-of-household Saver's Credit cap for 2025 is $59,250 (Internal Revenue Service, 2025), and $57,000 is $2,250 under it, so she qualifies. The credit counts a maximum of $2,000 of her contribution at a rate of 10% to 50% (Internal Revenue Service, 2025): at the 10% rate that is 0.10 × $2,000 = $200; at the 50% rate it is 0.50 × $2,000 = $1,000. Form 8880 sets which rate applies to her income; the result goes on Schedule 3 (Form 1040), line 4.
Roth IRA. The same $7,000 is allowed — $64,000 is well below the $150,000 head-of-household Roth threshold (Internal Revenue Service, 2025) — but it is not deductible (Internal Revenue Service, 2025). Her AGI stays at $64,000, which is $4,750 above the $59,250 cap, so her Saver's Credit is $0.
The difference for 2025. Traditional: AGI $57,000 and a credit of at least $200. Roth: AGI $64,000 and a credit of $0. The credit alone is a $200 minimum swing — $1,000 at the top rate — on top of $7,000 less taxable income.
The knife edge is real. If Dana's pre-contribution AGI were $66,500, the same $7,000 deduction leaves $59,500, which is $250 over the $59,250 cap, and the credit drops to $0.
What the traditional side costs her later: distributions are includible in taxable income, and withdrawals before age 59½ may carry a 10% additional tax (Internal Revenue Service, undated). She must begin required minimum distributions in the year she turns 73 (Internal Revenue Service, undated). The Roth has no required minimum distributions (Internal Revenue Service, undated).
What Could Change the Answer
- A raise or a new job with a workplace plan. Single or head of household covered at work: the deduction goes partial above $79,000 and disappears at $89,000 of modified AGI (Internal Revenue Service, 2025). Crossing $89,000 makes the Roth the only one of the two with a tax effect.
- Marriage. Two singles at $90,000 each file jointly at $180,000: above the $146,000 joint deduction cut-off if covered at work, but still under $236,000, so full Roth contributions remain available (Internal Revenue Service, 2025).
- Filing separately while living together. The Roth phases out from more than $0 and is barred at $10,000 of modified AGI, and the deduction is gone at $10,000 if you are covered at work (Internal Revenue Service, 2025). Both doors close almost immediately.
- Leaving an employer plan for a whole year. If neither you nor your spouse was covered for any part of the year, the deduction returns at the lesser of $7,000 ($8,000 at 50+) or 100% of compensation, with no phase-out (Internal Revenue Service, 2025).
- A home sale or other one-off gain. A taxable gain that lifts single modified AGI to $165,000 or more bars the Roth contribution entirely (Internal Revenue Service, 2025); the fallback is a nondeductible traditional contribution on Form 8606.
- An income drop. Falling to $39,500 or less of AGI as a single filer, or $79,000 filing jointly, opens the Saver's Credit at 10% to 50% of up to $2,000 per person (Internal Revenue Service, 2025) — and a traditional deduction is the lever that can pull AGI under the cap.
- Turning 50. The limit rises from $7,000 to $8,000 for both account types (Internal Revenue Service, 2025), which widens the deduction and moves the Saver's Credit math.
- A spouse with little or no compensation. Filing jointly, the Kay Bailey Hutchison Spousal IRA deduction for the lower-compensated spouse is limited to the lesser of $7,000 ($8,000 at 50 or older) or combined compensation minus certain amounts (Internal Revenue Service, 2025).
- Turning 73. Required minimum distributions start on the traditional IRA (Internal Revenue Service, undated), and SEP-IRA and SIMPLE-IRA owners and employees over 73 must take them even if still working (Internal Revenue Service, undated). The Roth has none.
Frequently asked questions
Can I split $7,000 between a traditional IRA and a Roth IRA?
Yes, but $7,000 for 2025 ($8,000 at age 50 or older) is the combined limit across both, not per account (Internal Revenue Service, 2025). Splitting means only the traditional share can be deductible, since Roth contributions are never deductible.
I earn too much for a Roth. What is left?
Above $165,000 single or $246,000 married filing jointly, no Roth contribution is permitted (Internal Revenue Service, 2025). A nondeductible traditional IRA contribution is still possible, and it must be reported on Form 8606, Nondeductible IRAs.
Does a Roth IRA contribution ever change my refund?
Not through a deduction — Roth contributions are never deductible (Internal Revenue Service, 2025). It can still count toward the Saver's Credit, up to $2,000 per person at a 10% to 50% rate, figured on Form 8880 (Internal Revenue Service, 2025).
Do I have to file anything to open a Roth IRA?
No form is required just to contribute to a Roth IRA (Internal Revenue Service, 2025). Form 8606 is required only when you make nondeductible contributions to a traditional IRA.
Which one avoids forced withdrawals?
The Roth IRA — no required minimum distributions are required for it (Internal Revenue Service, undated). A traditional IRA requires RMDs each year beginning with the year you turn 73 (Internal Revenue Service, undated).
Sources
- Internal Revenue Service — Publication 590-A (2025), Contributions to Individual Retirement Arrangements (IRAs) (2025)
- Internal Revenue Service — Retirement Plans FAQs regarding IRAs Distributions (Withdrawals)
Written by
Desmond Okafor
Desmond covers personal finance with an eye for the small decisions that compound into big outcomes. He's drawn to budgeting tools, debt payoff strategies, and the psychology behind spending. He writes for readers who feel behind and want a clear next step.