Finance
Married Filing Jointly vs. Married Filing Separately: What Actually Changes Your Bill
The two statuses use different brackets, deduction limits and eligibility rules — but only a handful of those differences usually move your final number.
By Priya Chandrasekaran · Oct 06, 2026 · 10 min read
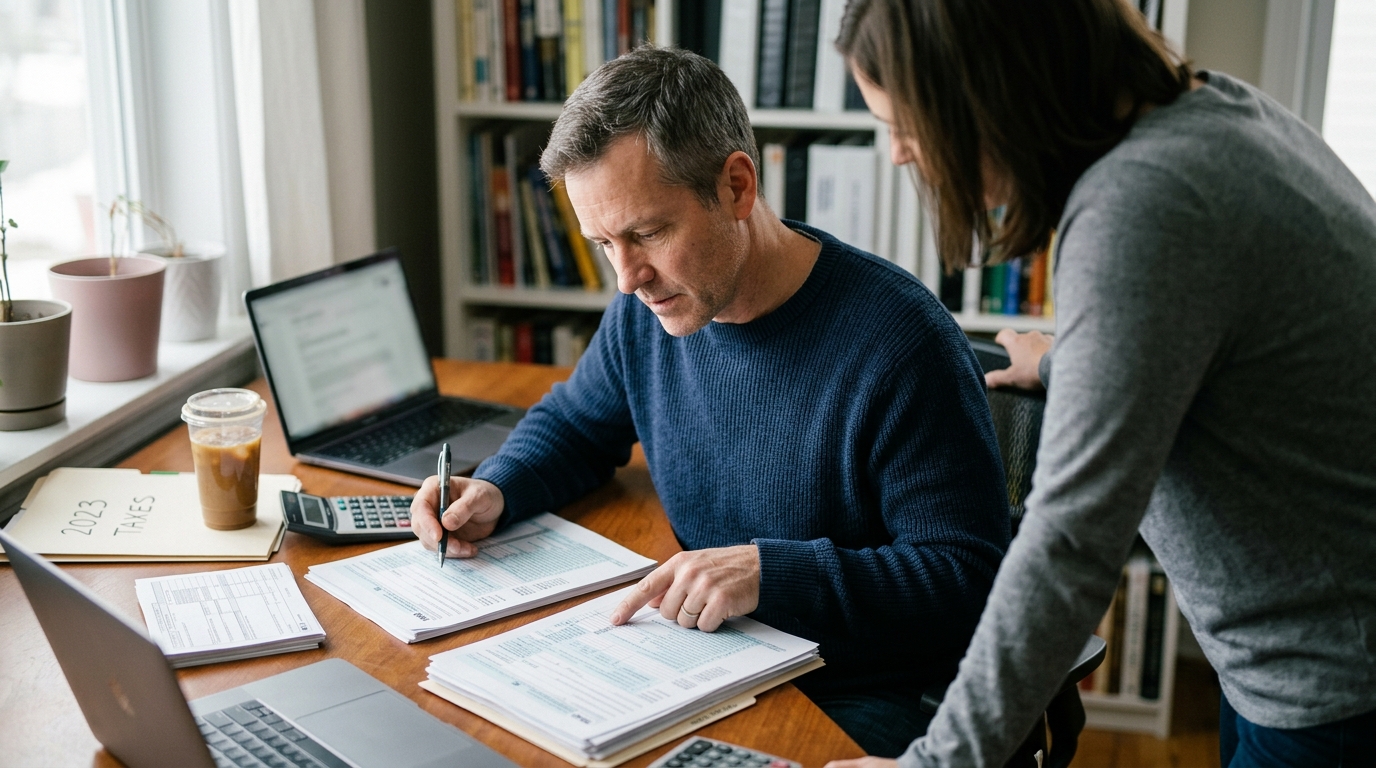
Married couples get two choices on the top of Form 1040, U.S. Individual Income Tax Return: married filing jointly or married filing separately. The brackets and standard deductions for separate filers are set at roughly half the joint figures, so for most couples the split itself is tax-neutral. What actually changes the bill is the list of deductions and credits that separate filers lose, the halved limits on things like capital losses, and the surtax thresholds that kick in at half the joint level.
This guide lays the two side by side on identical criteria, gives you a sequence of checks you can run with your own numbers, and works one example through to an exact dollar difference.
The Two Options, Side by Side
Both statuses use the same return — Form 1040, U.S. Individual Income Tax Return — and the same Schedule A (Form 1040), Itemized Deductions if you itemize. The difference is in the numbers each status is allowed to use.
| Criterion | Married filing jointly | Married filing separately |
|---|---|---|
| 2025 standard deduction | $31,500 (Jackson Hewitt, 2025) | $15,750 each (Jackson Hewitt, 2025); the IRS worked example enters $15,750 on Form 1040 line 6 (Internal Revenue Service, 2025) |
| 2024 standard deduction | $29,200 (Internal Revenue Service, 2024) | $14,600 each (Internal Revenue Service, 2024) |
| Top of the 10% bracket, 2025 | $23,850 of taxable income (Internal Revenue Service, 2025) | $11,925 of taxable income (Internal Revenue Service, 2025) |
| Where the 37% rate starts, 2025 | Above $751,600 (Internal Revenue Service, 2025) | Above $375,800 (Internal Revenue Service, 2025) |
| Must file a return at | Varies with the joint gross income threshold for the year | $5 of gross income, regardless of age, for 2025 (Internal Revenue Service, 2025) |
| Capital loss against ordinary income | $3,000 (Internal Revenue Service, 2025) | $1,500 (Internal Revenue Service, 2025) |
| Student loan interest deduction | Up to $2,500 per return, even if both spouses paid more (Yahoo Finance, undated) | $0 — the status is excluded (SmartAsset, undated) |
| Standard deduction if the other spouse itemizes | Not applicable — one return, one method | $0 standard deduction; you must itemize too (Internal Revenue Service, undated and 2024) |
| Additional Medicare Tax threshold, Form 8959, Additional Medicare Tax | $250,000 (Internal Revenue Service, 2025) | $125,000 (IRS via Healthgrades summary, undated) |
| Net Investment Income Tax, Form 8960, Net Investment Income Tax | Statutory threshold listed in the current Form 8960 instructions | $125,000 modified AGI (SmartAsset citing IRS Form 8960 thresholds, undated) |
| AMT exemption, 2025, Form 6251, Alternative Minimum Tax—Individuals | $137,000 (HREM CPA citing IRS Rev. Proc. 2024-40, 2024) | $68,500 (HREM CPA citing IRS Rev. Proc. 2024-40, 2024) |
| Traditional IRA deduction phase-out if covered by a workplace plan | Annual inflation-adjusted range published by the IRS | $0 to $10,000 of MAGI, fixed, never inflation-adjusted (Internal Revenue Service, 2025) |
| Roth IRA contribution phase-out | Annual inflation-adjusted range | $0 to $10,000, no cost-of-living adjustment (Internal Revenue Service, 2025) |
Read the bracket rows together with the deduction rows. Two separate filers each getting $15,750 in 2025 reach the same $31,500 as one joint return, and each separate 10% band of $11,925 adds to the joint $23,850. The structure is deliberately parallel. The rows that are not parallel — $1,500 instead of $3,000, $0 instead of $2,500, $68,500 instead of $137,000 — are where your bill actually changes.
How to Tell Which One Applies to You
Run these in order with your own figures. Stop when you hit one that clearly costs you money.
- Check the filing requirement first. If you file separately for 2025, you must file a return once your gross income reaches $5, regardless of age (Internal Revenue Service, 2025). A spouse with almost no income cannot simply skip filing once you choose separate returns.
- Compare deduction methods, not just amounts. If either spouse itemizes on Schedule A (Form 1040), Itemized Deductions, the other cannot take the standard deduction at all (Internal Revenue Service, undated; Internal Revenue Service, 2024). Add both spouses' itemized totals. If that combined figure is below the 2025 joint standard deduction of $31,500 (Jackson Hewitt, 2025), itemizing separately loses money.
- List what separate filing switches off. Student loan interest is the common one: up to $2,500 per return jointly (Yahoo Finance, undated) and $0 separately (SmartAsset, undated). Multiply the lost deduction by your bracket rate — in the 10% band, which runs to $11,925 of taxable income for a separate filer in 2025 (Internal Revenue Service, 2025), $2,500 of lost deduction is $250 of tax.
- Check capital losses. If you have more than $1,500 of net capital loss, separate filing caps the deduction at $1,500 instead of $3,000 (Internal Revenue Service, 2025).
- Check retirement contributions. If you are covered by a workplace plan and file separately, your traditional IRA deduction phases out between $0 and $10,000 of MAGI, a band that is never inflation-adjusted, and the same $0 to $10,000 band applies to Roth IRA contributions (Internal Revenue Service, 2025). One exception: if you lived apart from your spouse for the entire year, the single MAGI limits apply instead for the traditional IRA deduction (TurboTax Community, undated).
- Check the surtax thresholds if either income exceeds $125,000. Form 8959, Additional Medicare Tax, uses $250,000 jointly (Internal Revenue Service, 2025) and $125,000 separately (IRS via Healthgrades, undated). Form 8960, Net Investment Income Tax, uses a $125,000 modified AGI threshold for separate filers (SmartAsset citing IRS Form 8960 thresholds, undated).
- Check the AMT exemption if you are near it. For 2025 it is $137,000 jointly and $68,500 separately (HREM CPA citing IRS Rev. Proc. 2024-40, 2024), so splitting does not create extra exemption room.
- Weigh the non-tax reasons last. Separate filing "may benefit you if you want to be responsible only for your own tax" rather than your spouse's (Internal Revenue Service, 2025), and under income-driven student loan repayment plans it limits the servicer's payment calculation to your own income rather than combined spousal income (SoFi, undated). Those can outweigh a few hundred dollars of extra tax.
Worked Example
A married couple, both under 65, both covered by workplace retirement plans, filing for 2025. Spouse A has wages of $27,000 and a net capital loss of $3,000. Spouse B has wages of $25,000 and paid $2,500 of student loan interest. Combined wages: $52,000.
Married filing jointly. Start at $52,000. Subtract the $2,500 student loan interest deduction, which is capped at $2,500 per return (Yahoo Finance, undated): $49,500. Subtract the full $3,000 capital loss (Internal Revenue Service, 2025): $46,500. Subtract the 2025 joint standard deduction of $31,500 (Jackson Hewitt, 2025): taxable income $15,000. That sits inside the 10% band, which runs to $23,850 jointly (Internal Revenue Service, 2025). Tax: $15,000 × 10% = $1,500.
Married filing separately. Spouse A: $27,000 minus the capital loss deduction, limited to $1,500 for a separate filer (Internal Revenue Service, 2025), is $25,500. Minus the $15,750 separate standard deduction (Internal Revenue Service, 2025) leaves taxable income of $9,750, inside the separate 10% band that runs to $11,925 (Internal Revenue Service, 2025). Tax: $975.
Spouse B: $25,000 with no student loan interest deduction, because married filing separately is excluded from that deduction (SmartAsset, undated). Minus $15,750 leaves taxable income of $9,250. Tax: $925.
Combined separate tax: $975 + $925 = $1,900.
Difference: $1,900 − $1,500 = $400 more tax by filing separately. Note what did not cause it. The standard deductions are identical either way: $15,750 × 2 = $31,500. The brackets are identical: $11,925 × 2 = $23,850. The entire $400 comes from the $2,500 student loan interest deduction disappearing ($250 at 10%) and the capital loss being halved from $3,000 to $1,500 ($150 at 10%).
The same couple might still file separately if Spouse B is on an income-driven repayment plan, because the servicer would then calculate the payment on $25,000 rather than $52,000 (SoFi, undated). That is a comparison between $400 of extra tax and twelve months of payment difference, which you can only settle with your servicer's own payment figure for each income.
What Could Change the Answer
- One spouse starts itemizing. The moment either spouse itemizes on Schedule A (Form 1040), Itemized Deductions, the other's standard deduction drops to $0 (Internal Revenue Service, undated; Internal Revenue Service, 2024). A couple whose combined itemized deductions land below the 2025 joint figure of $31,500 (Jackson Hewitt, 2025) will usually give up money by filing separately.
- A raise past $125,000. Separate filers hit the Additional Medicare Tax at $125,000 on Form 8959, Additional Medicare Tax (IRS via Healthgrades, undated), versus $250,000 on a joint return (Internal Revenue Service, 2025). A single high earner can trigger the surtax separately that the couple would not owe jointly — but an evenly-paid couple at, say, $150,000 each would cross $250,000 jointly either way.
- A home sale or stock sale producing investment income. The Net Investment Income Tax on Form 8960 reaches separate filers at $125,000 of modified AGI (SmartAsset citing IRS Form 8960 thresholds, undated). A one-year gain can put a separate filer over a threshold the couple's normal income never approaches.
- A large net capital loss. Above $1,500 of loss, separate filing starts wasting it: the cap is $1,500 separately against $3,000 jointly (Internal Revenue Service, 2025).
- Opening or funding an IRA while covered by a workplace plan. Filing separately pins the traditional IRA deduction phase-out to a fixed $0–$10,000 MAGI band and the Roth contribution phase-out to the same $0–$10,000, neither inflation-adjusted (Internal Revenue Service, 2025). Almost any wage income puts you over it.
- Living apart for the full year. If you did not live with your spouse at any point during the year, you are treated under the single MAGI limits for the traditional IRA deduction instead of the $0–$10,000 separate band (TurboTax Community, undated).
- Entering or leaving an income-driven student loan repayment plan. Filing separately limits the payment calculation to your own income (SoFi, undated), but it also removes the student loan interest deduction of up to $2,500 (SmartAsset, undated; Yahoo Finance, undated).
- Doubt about a spouse's reporting. Filing separately "may benefit you if you want to be responsible only for your own tax" (Internal Revenue Service, 2025). That is a liability decision, not an arithmetic one, and it can justify paying more.
Frequently asked questions
Is the standard deduction really half on a separate return?
Yes. For 2025 it is $15,750 for married filing separately against $31,500 for married filing jointly (Jackson Hewitt, 2025), and for 2024 it was $14,600 against $29,200 (Internal Revenue Service, 2024). Two separate filers reach the same total.
Can one of us itemize while the other takes the standard deduction?
No. Under married filing separately, if your spouse itemizes you cannot take the standard deduction (Internal Revenue Service, undated). Both spouses must use the same method (Internal Revenue Service, 2024), so one spouse's choice can wipe out the other's $15,750 for 2025.
Does my spouse have to file if they earned almost nothing?
Under married filing separately, a 2025 return is required once gross income reaches $5, regardless of age (Internal Revenue Service, 2025). On a married filing jointly return, both spouses' income goes on one return instead.
Will filing separately lower my student loan payment?
Married filing separately limits an income-driven repayment calculation to your own income rather than combined spousal income (SoFi, undated). The trade-off is losing the student loan interest deduction of up to $2,500 that married filing jointly allows (Yahoo Finance, undated).
Sources
- Internal Revenue Service — Publication 501 (2024), Dependents, Standard Deduction, and Filing Information (2024)
- Internal Revenue Service — Publication 501 (2025), Dependents, Standard Deduction, and Filing Information (2025)
Written by
Priya Chandrasekaran
Priya breaks down earnings calls, mergers, and balance sheets for readers who don't speak spreadsheet. She's most interested in how companies justify the numbers they report. Her columns favor clarity over jargon.