Finance
Notice of Default on Your Car Loan: What You Must Do Before Repossession
A notice of default on a secured auto loan starts a clock measured in days, not months, and the cure window written on it varies by state.
By Priya Chandrasekaran · Oct 06, 2026 · 9 min read
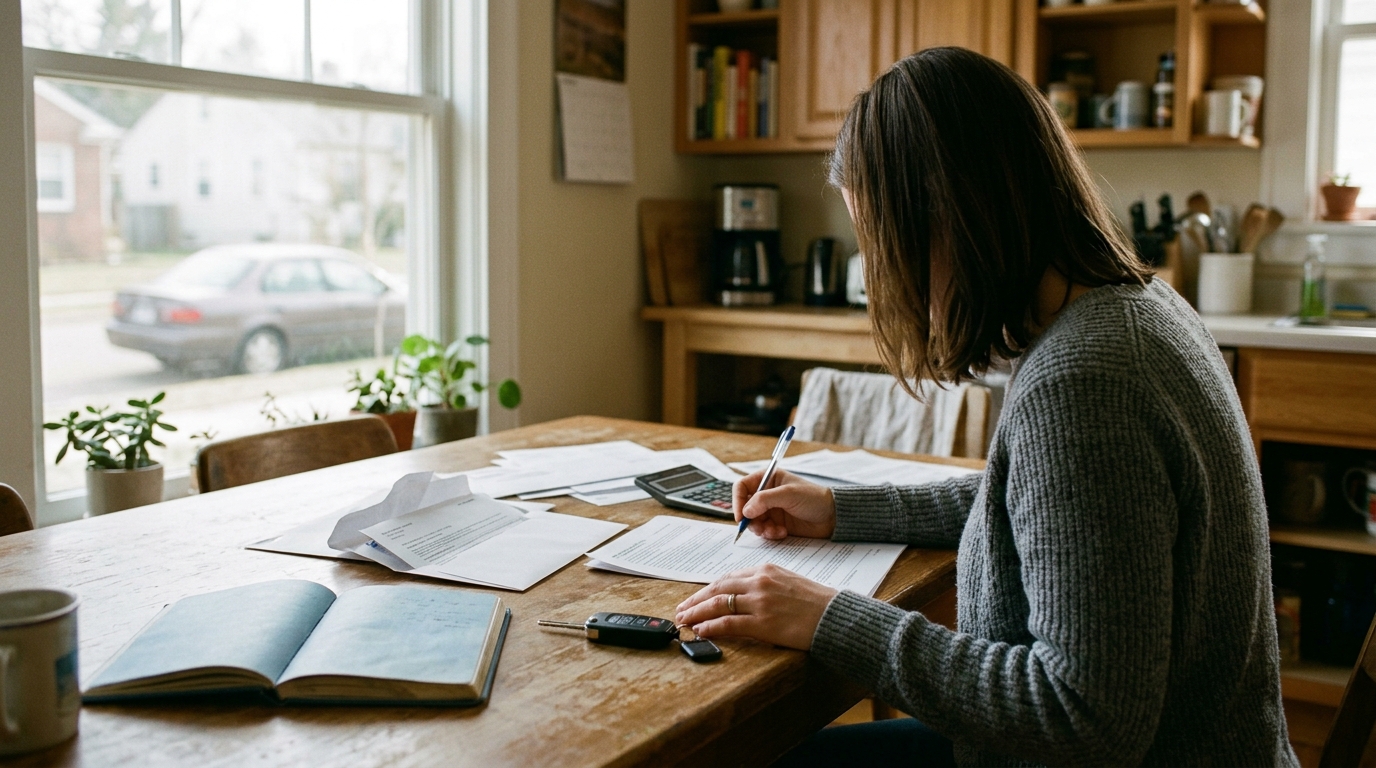
A notice of default on a car loan is not the same document as a notice of repossession, and the gap between them is often measured in days. Auto loans are secured installment debt: the car is the collateral, and in many states the lender does not need a court order to take it back (Federal Trade Commission, undated). What protects you is the cure window written into your state's law and your retail installment contract — and that window starts on the date printed on the notice.
This guide walks the day-by-day sequence from missed payment to sale, the actions you can complete today, and the exact words to use on the phone with the servicer or collection agency.
What Happens and When
Auto loans have no single federal default day-count. A federal student loan defaults after 270 days of missed payments (Federal Student Aid, undated), and a credit card account more than 180 days past due must generally be charged off by the issuer (National Consumer Law Center, undated). A car loan is different: default is defined by your retail installment contract and your state's law, and it can be triggered within days.
- Day 1 after the due date. The payment is late and the late fee in your contract applies. Nothing is repossessed on this day.
- Day 10 (South Carolina example). A payment 10 days late can put a borrower in default, and the lender must send a one-time Notice of Right to Cure (South Carolina Legal Services, undated). Find the comparable rule for your state before you assume you have a month.
- Day 0 on the notice — the date printed at the top. Your cure clock starts here, not on the day you opened the envelope.
- Day 20 from the notice date. South Carolina gives 20 days to get out of default before repossession (South Carolina Legal Services, undated). Iowa requires the creditor to describe the default, state the steps to resolve it, and allow 20 days to correct it before repossessing (News Tribune citing Iowa law, 2012).
- Day 21 from the notice date (Massachusetts). The Right to Cure notice gives 21 days to bring the loan current before repossession can begin, under M.G.L. c. 255B, §20A (Nortridge, undated).
- The day after the cure window closes. In many states the lender can repossess without going to court and without telling you first, depending on your contract and state law (Federal Trade Commission, undated). If your contract includes a starter interrupt or kill switch, disabling the car for nonpayment might be treated as a repossession or as a breach of the peace, again depending on contract and state law (Federal Trade Commission, undated). Call the servicer's loss-mitigation line the moment the cure date passes and ask whether the account has been assigned to a recovery agent.
- Within 5 days of repossession (Ohio example). Lenders must send a notice of default and right to cure, and must give written notice of the time and place of any public sale (LoanPro, undated).
- At least 10 days before the sale. Lenders in every state must send a notice telling you when the car will be sold (Nolo, undated). For a public sale, the lender must give the date, time and place; for a private sale, the date the vehicle could be sold (Consumer Financial Protection Bureau, undated).
- Any time before that sale happens. You may be entitled to redeem the car by paying the full loan amount plus repossession costs (Consumer Financial Protection Bureau, undated). Ask for the redemption figure in writing the same day the sale notice arrives.
- After the sale. You owe the deficiency balance. The CFPB's worked example: a $10,000 remaining balance, a $7,500 sale price, a $2,500 deficiency plus repossession fees (Consumer Financial Protection Bureau, undated).
- Within 5 days of a debt collector's first contact about that $2,500. The collector must tell you that you have 30 days to dispute the validity of the debt or any portion of it (Privacy Rights Clearinghouse, undated). That 30 days runs from the first communication, not from the sale.
What to Do Right Now
Each of these is finishable today.
- Write the date printed on the notice at the top of a sheet of paper, then count forward 20 days and 21 days and write both dates down. One of those is likely your cure deadline, depending on your state.
- Pull your retail installment contract and read the paragraphs headed "Default," "Acceleration," "Right to Cure," and any clause mentioning an electronic disabling or starter interrupt device (Federal Trade Commission, undated).
- Call the phone number printed on the notice and ask for one number: the exact dollar amount that cures the default, and the last calendar date it will be accepted.
- Ask on that same call whether the account is still with the servicer or has been placed with a third-party collection agency. The Fair Debt Collection Practices Act and Regulation F, effective November 30, 2021 (Consumer Financial Protection Bureau, undated), govern collectors — not every original creditor.
- Ask for a written payoff quote including repossession costs, which is the redemption figure if the car is already gone (Consumer Financial Protection Bureau, undated).
- Call your state attorney general's consumer protection line or your state's legal services office and ask one question: how many days does my state's right-to-cure notice give me?
- Check your bank account and autopay settings today so a scheduled payment does not bounce mid-negotiation.
- Remove personal property from the car and photograph the odometer and the body panels while the car is still in your possession.
- Start a call log with date, time and the representative's name. Collectors generally cannot contact you before 8 a.m. or after 9 p.m. in your time zone, cannot contact you at work once told your employer prohibits it, and cannot email or text once asked to stop (Federal Trade Commission, undated). Under Regulation F they generally may not call more than seven times within a seven-day period per debt, and must generally wait a week after speaking with you (Privacy Rights Clearinghouse, undated).
- If any of those limits are broken, file a complaint online with the Consumer Financial Protection Bureau or by calling the CFPB (New Economy Project, undated).
What to Say When You Call
Read these aloud. Keep the call log open.
Open by establishing who holds the loan
Say this
"I'm calling about account number [number]. Is this loan still with you as the servicer, or has it been placed with a third-party collection agency? Please give me the name and phone number of whoever holds it now."
Pin down the cure amount and the deadline
Say this
"What is the exact dollar amount that brings this account current, including all fees? What is the last calendar date you will accept it? My notice is dated [date] — confirm whether that date plus my state's cure period is the deadline you are working to."
Assert your rights if a collector is involved
Say this
"Under the Fair Debt Collection Practices Act, I dispute this debt and I am requesting validation in writing. I understand I have 30 days from your first communication to do that. Do not call me before 8 a.m. or after 9 p.m. in my time zone, and do not call me at work."
Ask about the car and the sale
Say this
"If the vehicle has already been repossessed, I intend to redeem it. Send me the full loan payoff plus repossession costs in writing. If it is going to public sale, I want the date, time and place; if private sale, the date it could be sold."
Get the agreement in writing before you pay
Say this
"Please email or mail me written confirmation of this arrangement — the amount, the due date, and a statement that no repossession will be ordered while I am performing under it. I will make the payment once I have that in writing."
If the car is taken after you completed what was agreed
Say this
"I completed the option your representative confirmed on [date]. The Consumer Financial Protection Bureau has said that a servicer's failure to prevent repossession after a borrower completes an agreed option to avoid it, where reasonably practicable given timing, may be an unfair act or practice. I am filing a complaint with the CFPB and I want this escalated."
Frequently asked questions
Can the lender take the car without telling me first?
In many states, yes — a lender may legally repossess without going to court or notifying you first, depending on your contract and state law (Federal Trade Commission, undated). That is not servicer discretion; it is set by your state's statute and the default clause in your retail installment contract. Several states override it with a mandatory pre-repossession notice: 20 days in South Carolina and Iowa, 21 days in Massachusetts under M.G.L. c. 255B, §20A.
If the car sells for less than I owe, do I have to pay the difference?
Under the contract you signed, the deficiency is owed: the CFPB's example is a $10,000 balance, a $7,500 sale price and a $2,500 deficiency plus repossession fees (Consumer Financial Protection Bureau, undated). Whether the lender or the collection agency that buys the account pursues the full $2,500, sues, or settles for less is their discretion — the holder of the debt decides, not a regulator.
Will the servicer accept a partial payment or push the payment to the end of the loan?
That is loss-mitigation and it sits entirely with the servicer's discretion; no federal rule requires an auto lender to offer a deferral or extension. What is not discretionary is the written confirmation: get the terms in writing before paying, because the CFPB has said that failing to prevent repossession after a borrower completes an agreed option, where reasonably practicable given timing, may be an unfair act or practice (Consumer Financial Protection Bureau, 2022).
Does the 270-day default rule apply to my car loan?
No. The 270-day rule is specific to federal student loans (Federal Student Aid, undated), and the 180-day past-due charge-off trigger is specific to credit card accounts (National Consumer Law Center, undated). An auto loan is secured installment debt, and its default date comes from your contract and your state's right-to-cure statute — check the date on your notice and count from there.
Sources
- Consumer Financial Protection Bureau — What happens if my car is repossessed?
- Consumer Financial Protection Bureau — Bulletin 2022-04: Mitigating Harm from Repossession of Automobiles (2022-02)
Written by
Priya Chandrasekaran
Priya breaks down earnings calls, mergers, and balance sheets for readers who don't speak spreadsheet. She's most interested in how companies justify the numbers they report. Her columns favor clarity over jargon.